• Skip to main content
  • Skip to primary sidebar

SpotGamma™

S&P 500 Stock Market Gamma Trading Levels Based on Options Open Interest

  • About
  • Pricing
  • Academy
  • Resources
    • Tool Demos
    • Case Studies
    • Blog
    • Support Center
    • Daily Report
    • Free Trading Tools
      • Opening Setup Free Report
      • Options Profit Calculator
      • SPX Gamma Exposure
      • Implied Earnings Moves
    • Report Card
  • Login

Nov 01 2019

Call Roll Gamma Trap

Most of the time when we talk about “gamma traps” people assume its a downside only event. I don’t think thats true. As I once read somewhere “gamma happens both ways”. There is evidence the last several days rise in stocks was caused by calls being rolled up.

If market makers are on the other side of short call positions that get rolled higher, they will have to reduce their short hedges (assuming dealers are net long calls, hedged with short stock). In other words they need to buy back stock – be it futures, SPY, etc.

The chart below shows a recent history of positive gamma. You can see over the last few days the 3025 & 3050 strike started decreasing in favor of 3075 and 3100. This is evidence that calls were being rolled up.
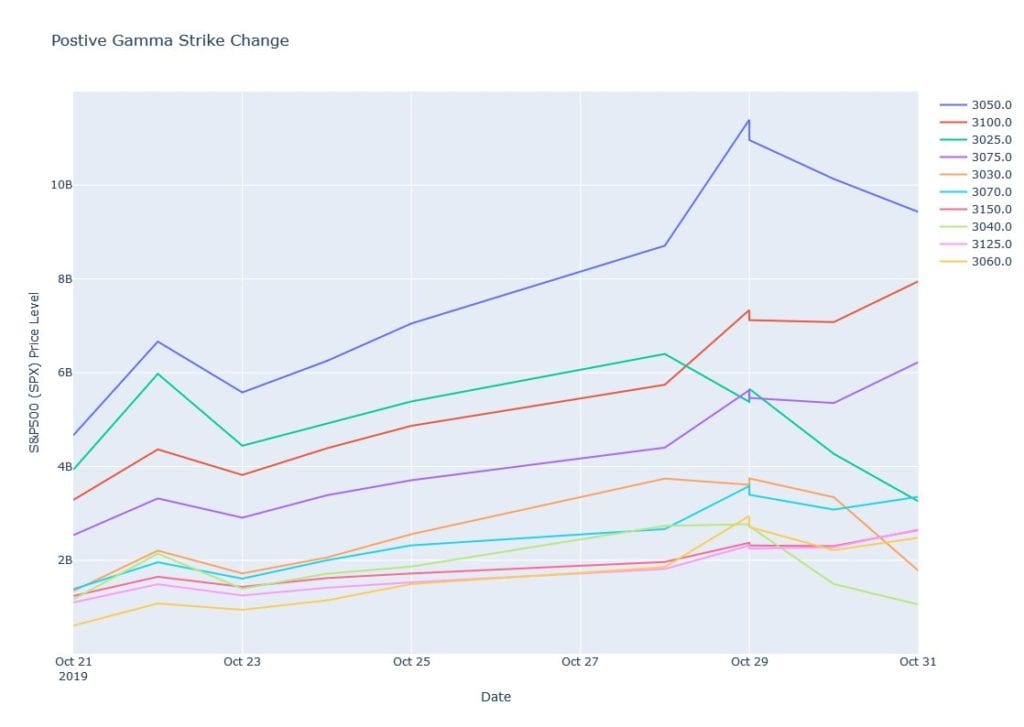
call gamma chart
Call Gamma Chart from SpotGamma.com

The other indication is price action in the S&P500 itself. The last two days were very sharp moves up into the market close which is indicative of hedging. I speculate this is hedging as the price action appears impervious to price – in other words its buying regardless of impact and it is pretty large size. If the price action were say, a mutual fund, they would not want to rip through prices. They would work the order over a day or some other timeframe that reduces price impact. See in the chart below the sharp moves up in the last 10 minutes of the cash close. Its mechanical in appearance.
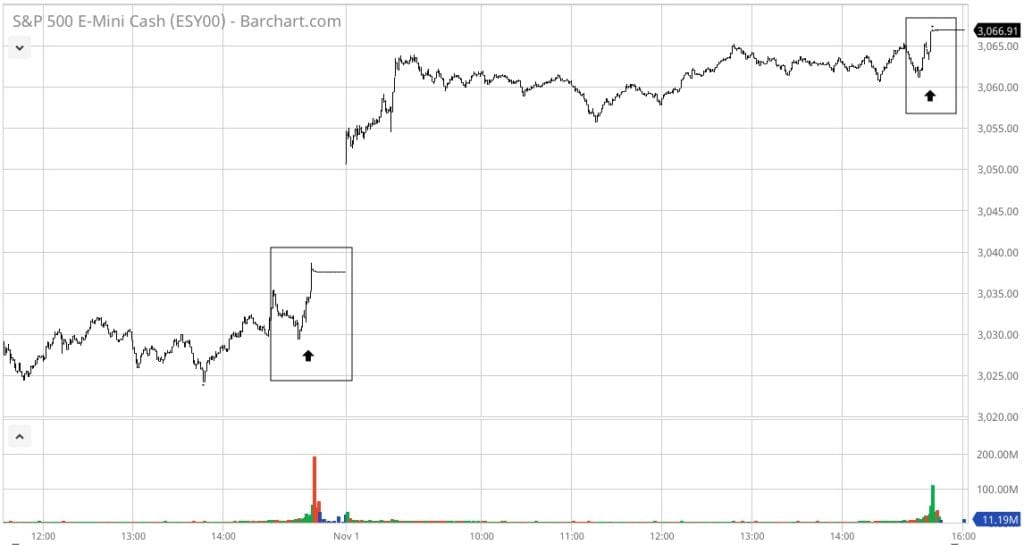
SPX E mini futures rise sharply just before the close

That brings us to the “Call Roll Gamma Trap” which is a result of both the roll but also the reflexivity of this action. Assuming dealers are net short puts and long calls, they are hedged with short futures. Puts obviously lose value as implied vols come in, causing more dealer stock buying. As dealers buy back hedges the higher market results in lower implied volatility (just look at the VIX smash) which results in lower options prices. This results in more dealer buying.

You can see how this cycle could become self-reinforcing and places a constant bid to the market.

Share This Article

  • Share
  • Twitter
  • LinkedIn
  • Reddit
  • Facebook

Written by SpotGamma · Categorized: Market Analysis · Tagged: call roll, gamma trap, options hedging

Don’t have an account with SpotGamma?

Choose the plan you want today to view unique support and resistance levels, access Founder’s Notes and expert commentary, daily trading ranges, and entrance into our private Discord.


Primary Sidebar

Related Resources

  • Hedges Rolled Down, Not Off: Brent Kochuba on Excess Returns

    Hedges Rolled Down, Not Off: Brent Kochuba on Excess Returns

    November 7, 2026
  • The Volatility Trap: What Options Markets Reveal About the Next Two Weeks

    The Volatility Trap: What Options Markets Reveal About the Next Two Weeks

    November 6, 2026
  • Tech Vol Collapsed, Put Skew Held Rich: Options Action Live on CNBC

    Tech Vol Collapsed, Put Skew Held Rich: Options Action Live on CNBC

    November 4, 2026
  • Gamma Guy: The 0DTE Flow That Usually Pins the Index Didn’t Arrive

    Gamma Guy: The 0DTE Flow That Usually Pins the Index Didn’t Arrive

    November 3, 2026
  • AMD Earnings Preview: Can AI Growth Overcome Rising Volatility and Expectations?

    AMD Earnings Preview: Can AI Growth Overcome Rising Volatility and Expectations?

    November 3, 2026
  • youtube
  • x
  • Privacy Policy
  • Disclaimer
  • Terms & Conditions
  • Support Center
  • Media
  • Contact Us

©2026 TenTen Capital LLC DBA SpotGamma

All SpotGamma materials, information, and presentations are for educational purposes only and should not be considered specific investment advice nor recommendations. Futures, foreign currency and options trading contains substantial risk and is not for every investor. An investor could potentially lose all or more than the initial investment. Risk capital is money that can be lost without jeopardizing one's financial security or lifestyle. Only risk capital should be used for trading and only those with sufficient risk capital should consider trading. Past performance is not necessarily indicative of future results. Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.

View Full Risk Disclosure