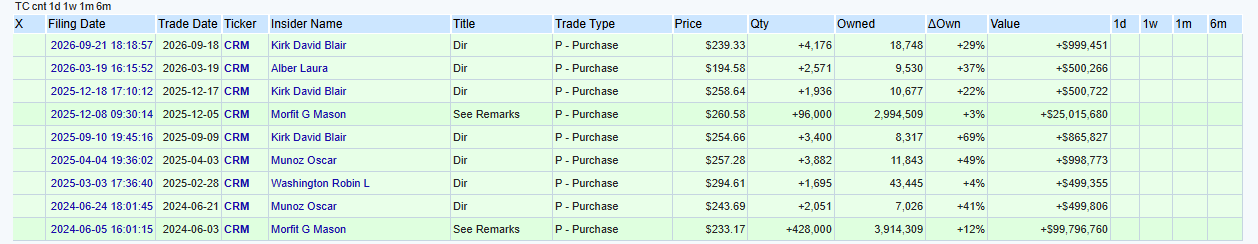
Salesforce director David Kirk bought 4,176 CRM shares on September 18 at an average $239.33, spending about $999,000 and increasing his direct holdings to 18,748 shares. That is a sizable increase of +29% to his stake. He also bought shares last December with another director also buying $500K of stock in March at favorable prices under $200/share.
An insider spending personal money is a constructive vote of confidence, but it does not establish a floor for the stock. The opportunity depends on whether Salesforce can turn strong demand for its AI products into faster growth across the whole business. (Source: SEC filing)
1. Options: Movement is priced in, direction is not
Implied volatility for the October 23 expiration is approximately 40%. The near-the-money $240 call and put together cost about $21.15, implying a roughly 8.8% move through the next month.
Earnings are not due until early December but often can move on peers in the software sector reporting their results.
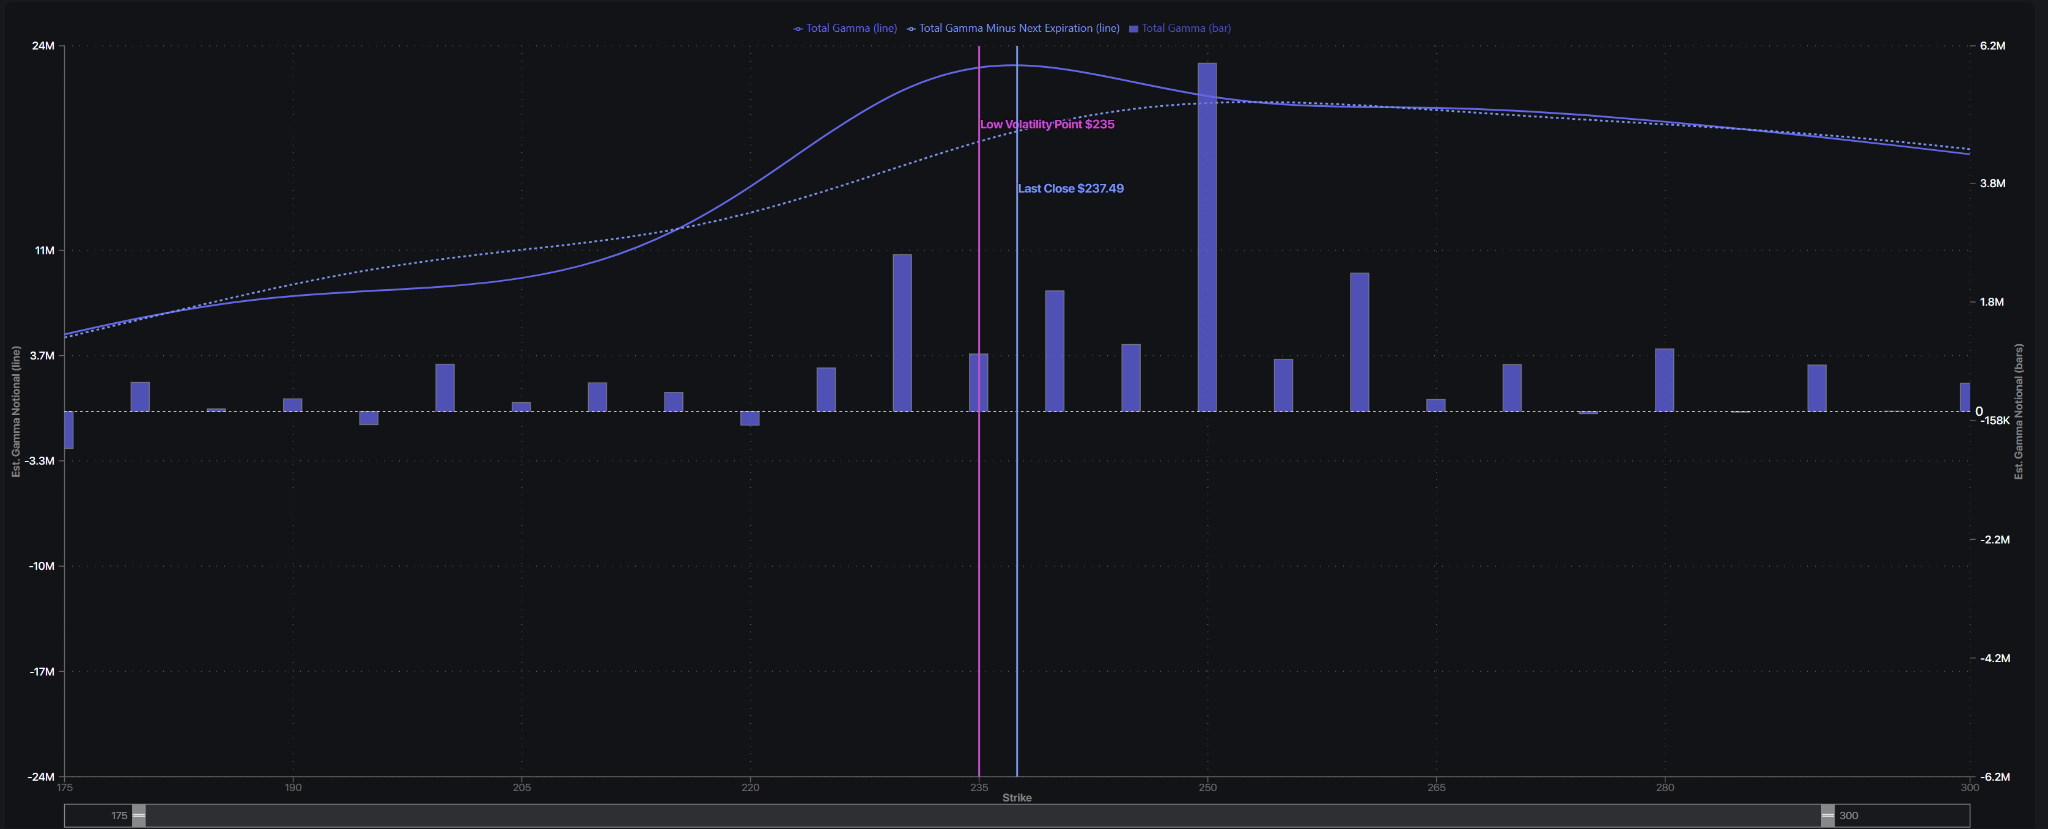
SpotGamma’s synthetic OI model below shows CRM entrenched in positive gamma positioning. The $250 strike is a large total gamma level that may be why the stock has retraced from that zone the past several weeks. SpotGamma’s positioning shows $230 as an important near-term options level, while the large concentration of gamma at $250 may help explain why the stock has struggled to extend through that area. With CRM now trading between those two levels, $230 and $250 provide useful reference points for the next directional move.
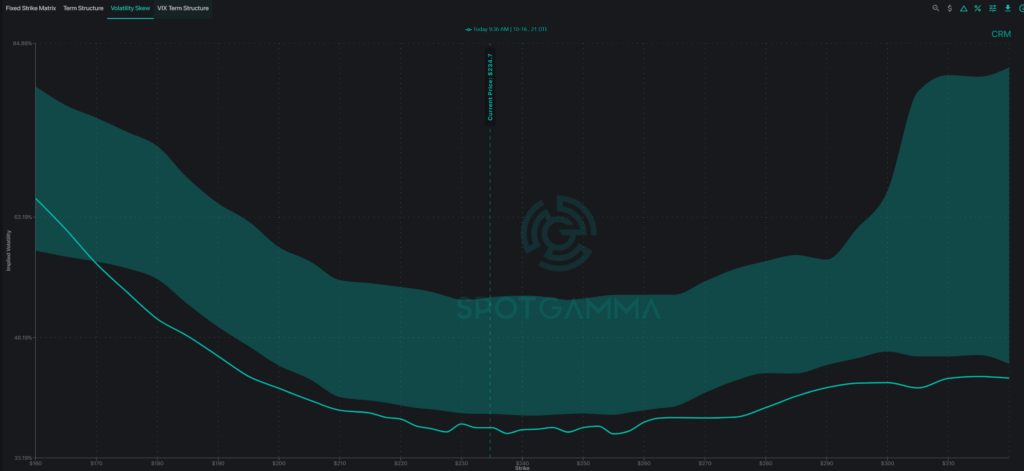
Options volatility skew is remaining calm despite the recent rally. The notable point is what the options market is not doing: despite the insider purchase, upside volatility has not become particularly expensive. Put skew remains modestly elevated and overall skew is subdued relative to its 90-day range. In other words, the insider is expressing conviction through stock while the options market has yet to price an unusually bullish outcome.
Looking at the SpotGamma vol skew chart below shows that implied volatility remains subdued. The IV skew is below 90 day averages as the teal line is below the average shaded area. The options market is simply assessing fair value to the stock at these levels while insiders are buying the stock.
2. Fundamentals: A solid business with an AI growth test
Salesforce generated $11.3 billion of fiscal second-quarter revenue, up 11% from a year earlier. Its current remaining performance obligation—contracted revenue expected over the next 12 months—rose 14% to $33.5 billion. Agentforce and Data 360 annual recurring revenue reached nearly $3.9 billion, up more than 210%. These numbers support the case that customers are buying into the AI platform.
The qualification matters: $456 million of quarterly revenue came from Informatica, and a little more than three percentage points of Salesforce’s projected 11%–12% full-year revenue growth comes from that acquisition. Management still expects only about 4%–5% full-year free cash flow growth. The bullish case improves if AI demand lifts organic sales, rather than simply adding fast-growing products within a slower-growing core. (Source: Salesforce Investor Relations)
3. Technicals: The buy is near a decision point
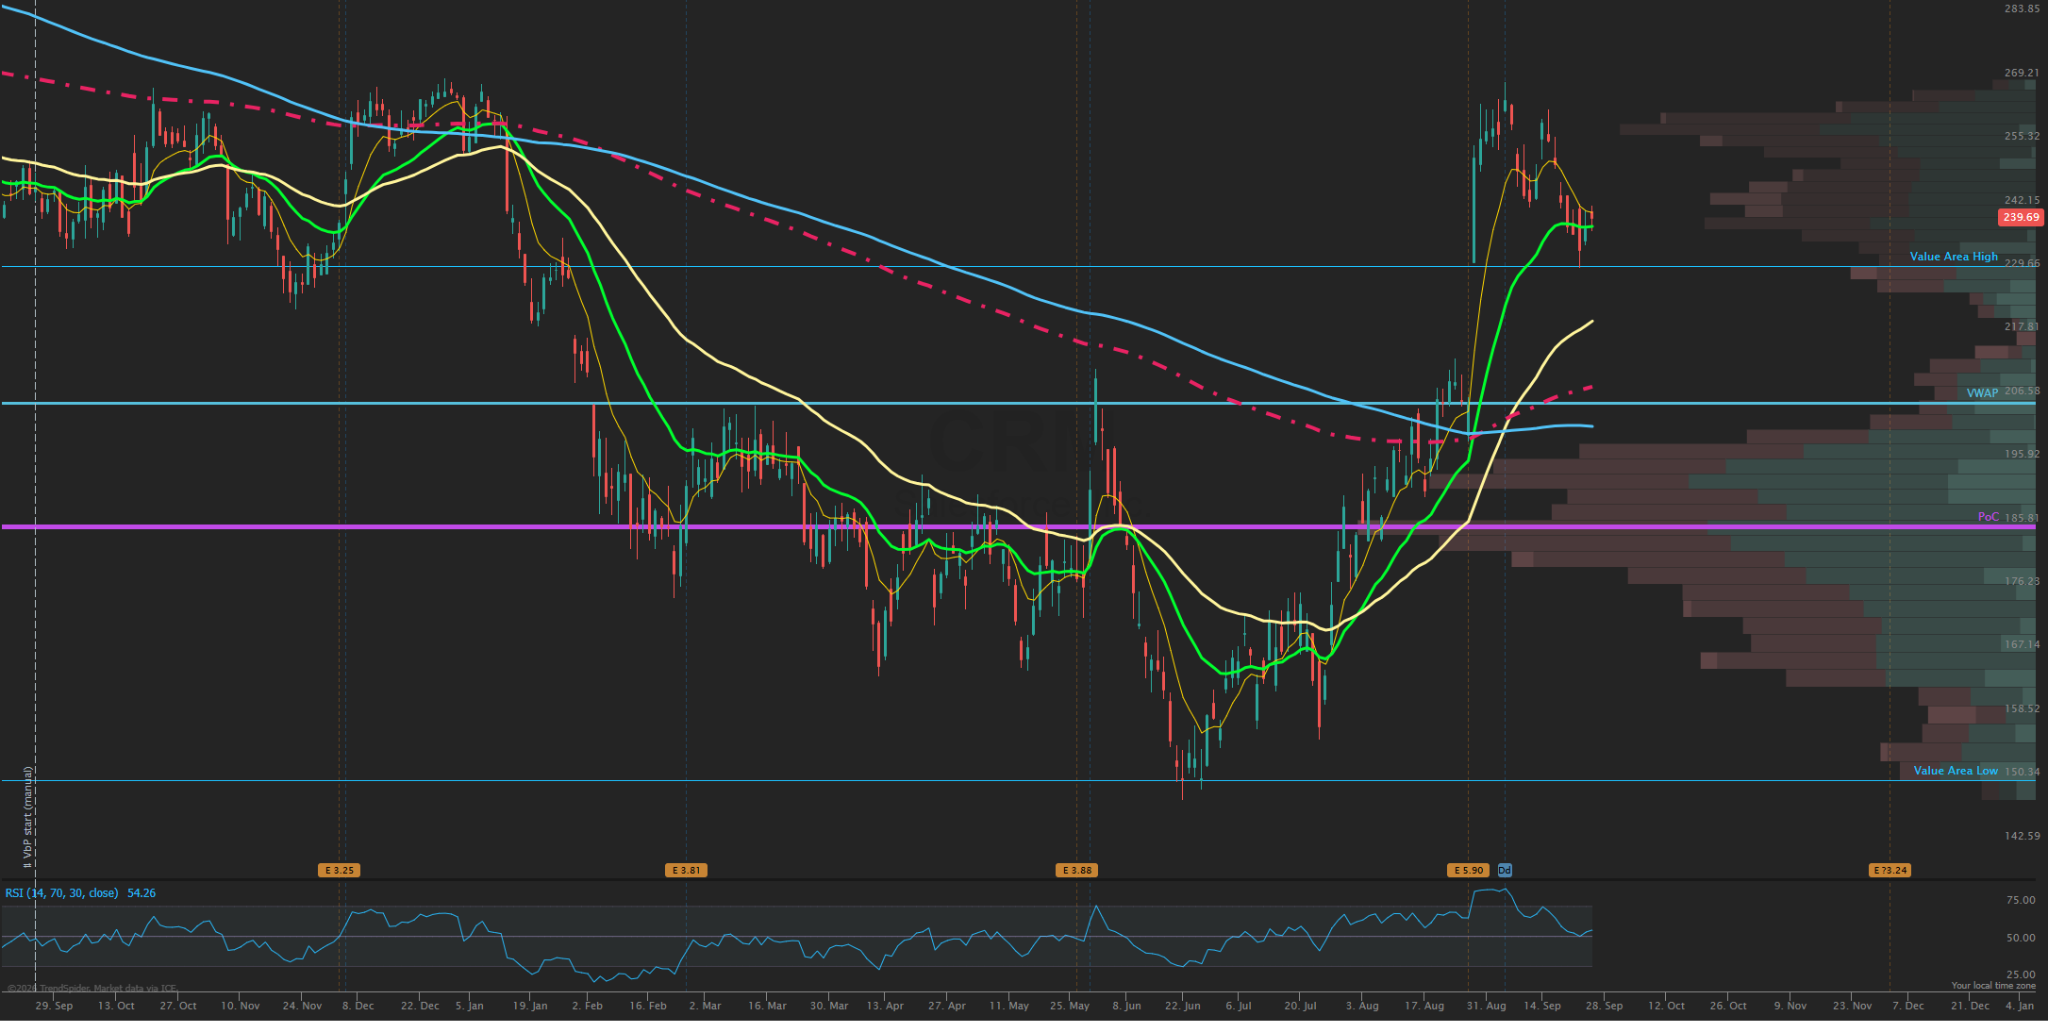
The recent 60%+ rally has been impressive but perhaps even more intriguing is the insider buying adding stock after a sizable rally off lows.
The $230 area is the first level to watch after the September 22 low of $229.81. A sustained recovery above roughly $242–$245 would suggest buyers are regaining control. A break below $230 would weaken the near-term rebound case as the open gap below becomes a vacuum, regardless of the insider purchase. These are chart reference levels, not guarantees of support or resistance.
The takeaway: Kirk’s nearly $1 million purchase is notable because it came after CRM had already rallied sharply from its summer lows—not during the selloff. Meanwhile, SpotGamma positioning identifies $230 as an important near-term level, with substantial gamma concentrated around $250.
Fundamentally, the question is whether rapid Agentforce and Data 360 adoption can translate into faster organic growth across Salesforce’s much larger core business. Until that becomes clearer, the insider purchase is best viewed as evidence of long-term conviction rather than a signal that the recent correction is necessarily over.
That creates a fairly clean setup: $230 is the level to watch on the downside, $250 is the key options level above, and the insider has just put roughly $1 million of his own capital to work between them.
Open-market insider purchases are generally more useful as signals of longer-term conviction than as short-term timing indicators. Kirk’s purchase therefore shouldn’t be read as a prediction that CRM has made its low at $230.