Markets are absorbing the Federal Reserve’s first rate hike since 2023 as another major catalyst approaches. President Donald Trump is scheduled to host Chinese President Xi Jinping in Washington on September 24. The meeting could affect trade, technology restrictions, critical-mineral supplies and market volatility.
The Fed raised its benchmark rate by 25 basis points to 3.75%-4.00%. Policymakers also projected one more increase by year-end, leaving markets sensitive to anything that changes the inflation outlook. (Reuters, September 16)
Trade policy matters because lower tariffs or fewer supply restrictions could reduce inflation pressure. New tariffs or tighter export controls could have the opposite effect.
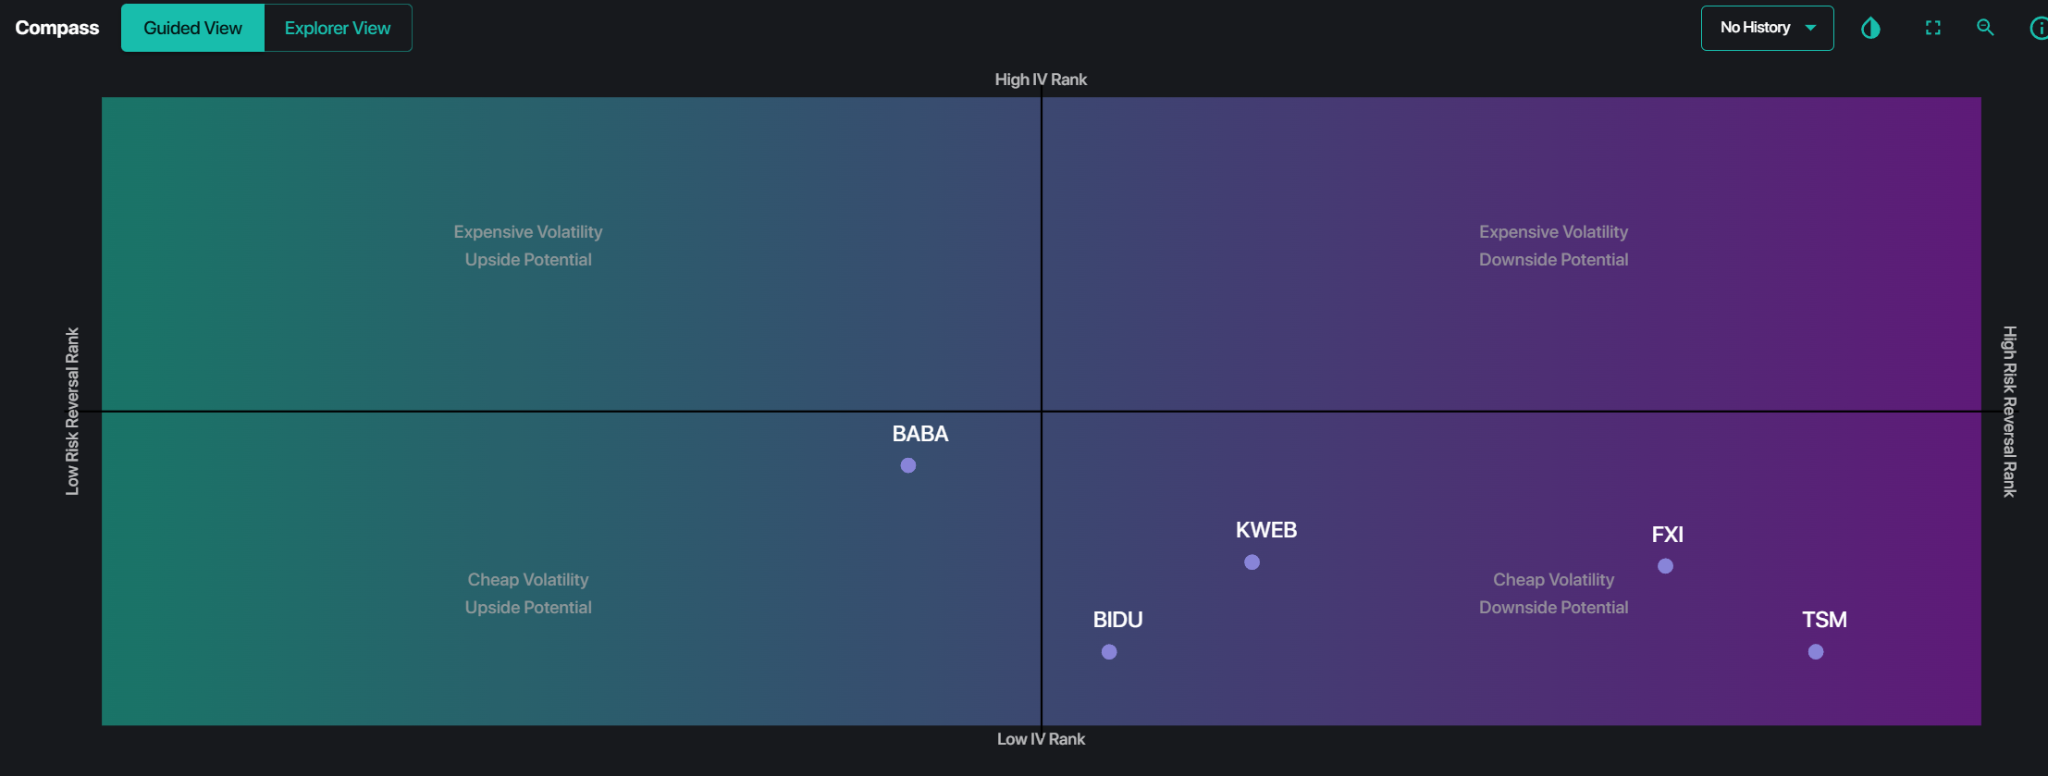
SpotGamma’s Compass shows relatively inexpensive implied volatility in several China-related stocks. Options may therefore be pricing a smaller move than the summit could produce, although cheap volatility does not predict market direction.
Key Issues for Markets
Trade and tariffs. Investors will look for tariff relief, new exemptions or a commitment to continued negotiations. Even limited progress could lower import costs and reduce the risk of another major trade conflict.
Rare earths. China controls much of the supply and refining capacity for several critical minerals. Some suppliers have restricted U.S. shipments of materials used in semiconductors, aerospace, defense and energy. Faster export approvals would ease pressure on manufacturers, while continued restrictions would keep supply risks elevated. (Reuters, September 13)
AI and semiconductors. Nvidia CEO Jensen Huang is expected to attend the state dinner, highlighting the importance of AI and chip policy. Investors will watch for any change in U.S. chip restrictions or Chinese measures affecting American technology companies. (Reuters, September 15)
Taiwan. Reuters reports that U.S. allies are watching for any change in Washington’s language on Taiwan or pending arms sales. Even a small shift could move semiconductor, defense and Asian markets because Taiwan is central to the global supply of advanced chips. (Reuters, September 17)
Three Market Scenarios
Positive outcome. Tariff relief, faster rare-earth approvals or an agreement to continue talks could support Chinese equities, semiconductors, industrials and import-dependent retailers. It could also help bonds if investors expect less supply-driven inflation.
Limited outcome. Friendly language without measurable policy changes could spark an initial rally that quickly fades.
Negative outcome. New tariff threats, tighter technology restrictions or conflict over Taiwan could strengthen the dollar, pressure emerging markets and lift volatility. Additional tariffs or supply restrictions could also keep inflation risks elevated, giving the Fed more reason to hold rates higher.
Retail Stocks Most Exposed to Trade
- Wayfair (W). Imported furniture and home goods make margins highly sensitive to tariffs.
- RH (RH). Tariff relief would lower costs on imported furniture. The stock is volatile and can react sharply to trade headlines.
- Five Below (FIVE). China sourcing and low price points leave less room to pass tariff costs to customers.
- Best Buy (BBY). Electronics sourced from China make prices, demand and margins sensitive to tariffs.
- Williams-Sonoma (WSM). Home-goods exposure remains meaningful, although the company has reduced its reliance on China.
- Dollar Tree (DLTR). Lower import costs would help protect margins and low price points.
- Target (TGT). Its broad imported assortment would benefit, but the effect is diluted across a larger business.
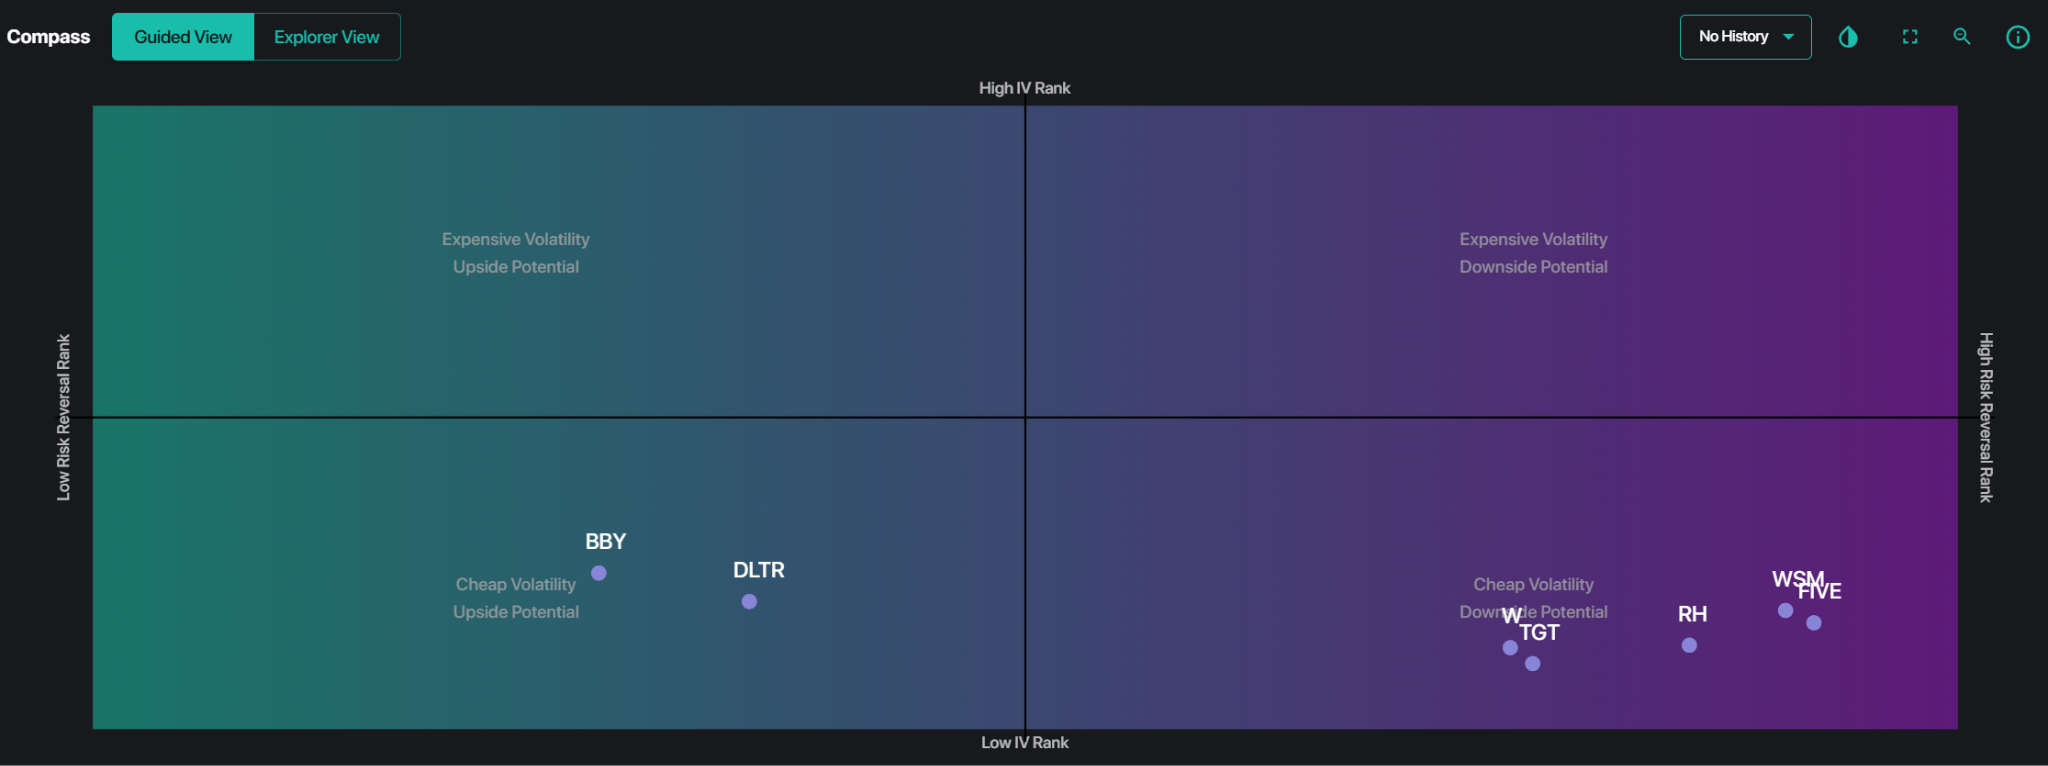
On SpotGamma’s retail Compass, BBY and DLTR sit in the cheap-volatility and upside-potential quadrant based on risk-reversal rankings. That makes them names to monitor, not automatic bullish trades.
The May 2025 tariff ceasefire provides a useful comparison. Wayfair gained about 22%, RH and Five Below about 18% each, Nike 7%, Best Buy 5% and Target 3% on the announcement. (MarketWatch, May 12, 2025)
Actual policy changes matter more than a positive tone. A meeting that produces no tariff reduction, exemption or supply agreement may create only a short-lived rally, especially in W and RH.
Options Signals to Watch
Several China-sensitive names still show relatively inexpensive implied volatility. Volatility could rise as September 24 approaches, especially in semiconductor stocks, Chinese equity ETFs and import-dependent retailers.
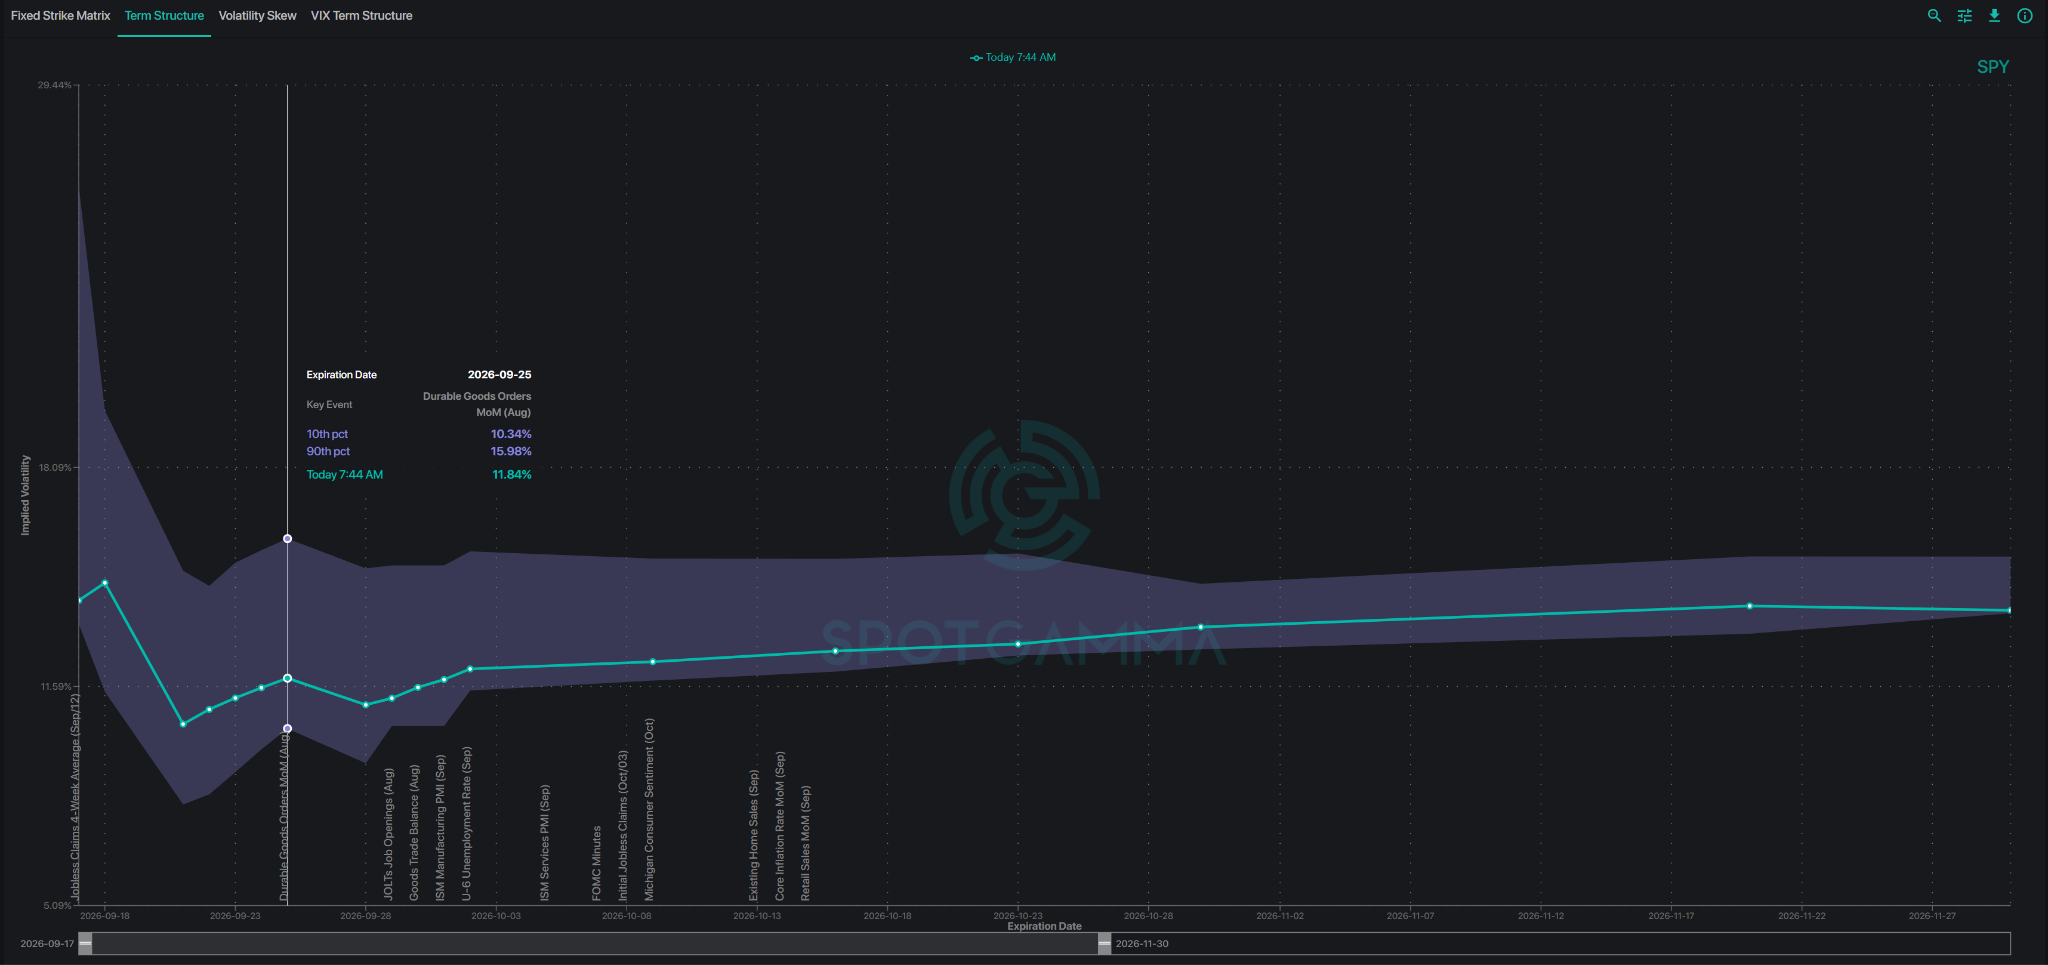
SPY’s term structure shows a modest rise in implied volatility for the September 25 expiration. The options market is assigning some extra risk to the summit, but not an extreme move. Durable-goods data follow on September 25, and the September jobs report is scheduled for October 2.
After the meeting, watch Treasury yields, the dollar and semiconductor leadership. Falling yields and stronger China-sensitive stocks would suggest investors see lower trade and inflation risk. A stronger dollar, rising yields and weaker semiconductors would point to greater risk.
Bottom line. The Fed has already tightened financial conditions. The summit will show whether trade policy eases that pressure or adds to it. Measurable progress could support risk assets, while new restrictions or tariff threats would likely increase volatility.