A diagonal spread is an options strategy that buys a longer-dated option and sells a shorter-dated option at a different strike — combining a directional view with the time-decay income of a calendar. The name comes from the option chain: the two legs sit diagonally across both strike and expiration. A call diagonal typically owns a back-month call at a lower strike and sells a front-month call at a higher strike, so the position profits if the stock drifts toward the short strike and then stalls there as the front option decays.
Key Takeaways
- A diagonal differs in both strike and expiration; a calendar differs only in expiration, a vertical only in strike.
- The ideal path is a grind toward the short strike, then a stall — direction plus pinning, not a breakout.
- Maximum loss is limited to the net debit paid, and the short leg’s rapid decay steadily reduces that cost basis.
- The structure is the engine inside the poor man’s covered call — a PMCC is simply a diagonal with a deep-ITM long leg.
How the Diagonal Spread Works
Two forces drive the trade, and both come back to extrinsic value. A near-dated option’s time premium decays fast — that is the leg you sell. A longer-dated option’s time premium decays slowly — that is the leg you own. Selling fast decay against slow decay means the position collects theta on net, like a calendar.
The diagonal adds direction by offsetting the strikes. Owning the lower strike and selling the higher one gives the package positive delta: you want the stock to rise. But unlike a plain bull call spread, you don’t want it to rise too far too fast. The maximum value at the front expiration occurs with the stock sitting right at the short strike — the short call expires worthless while your long call, with time remaining, is worth the most it can be relative to what you paid. Past the short strike, further gains in the long leg are increasingly offset by the short call going in the money.
That shape — profit peaking at the short strike at the front expiry — is why the diagonal is best understood as a calendar with a view: you are paid for a specific destination and a specific pause.
Example
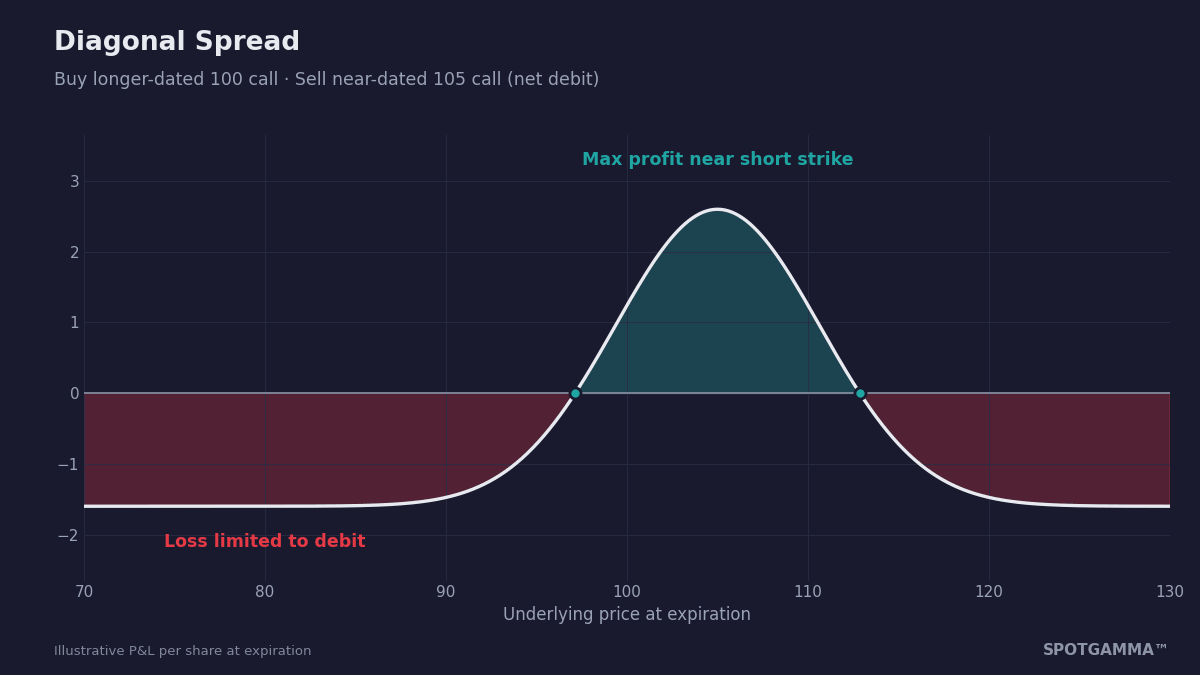
With the stock at $100:
- Buy one longer-dated $100 call.
- Sell one near-dated $105 call.
- Net debit: $1.60.
The profit tent peaks near $105 at the front expiration: the stock has drifted up to the short strike, the front call expires worthless, and the back-month $100 call retains its value plus the gains from the move. If the stock goes nowhere, the short call’s decay still offsets part of the long call’s slower bleed. If it collapses, the most you can lose is the $160 debit. Because the payoff depends on both price and time, this is a structure to model rather than eyeball — build it in SpotGamma’s free Options Calculator and watch how the tent shifts as the front expiration approaches.
Diagonal Spread vs. Related Strategies
- Vs. a calendar spread: the calendar uses the same strike in both months and is a pure pin-and-decay trade centered where the stock already is. The diagonal offsets the strikes to add a directional lean toward where you expect the stock to go.
- Vs. the poor man’s covered call: identical structure; the PMCC chooses a deep-ITM, high-delta long leg so the package behaves like stock replacement. A generic diagonal with an at-the-money long leg is a lighter-delta, more vol-sensitive trade.
- Vs. a double diagonal: run a call diagonal and a put diagonal simultaneously and you have a range trade with back-month protection on both sides.
Using Positioning Data to Trade It Better
The diagonal’s thesis — drift to a strike, then stall — is precisely what dealer positioning data describes. Like the rest of our options strategy library, the edge is letting the market’s structure choose the strikes:
- Sell the front month at the Call Wall. The Call Wall is the strike with the heaviest dealer gamma, where price has historically ground higher and then pinned. Selling the front-month call at the wall and owning the back month beneath it is the positioning-native construction: your profit peak sits exactly where hedging flows tend to park the stock.
- Check the gamma regime before entry. In positive gamma exposure (GEX) regimes, dealer hedging dampens moves and strikes tend to hold — the environment diagonals want. A negative-gamma tape that blows through strikes turns the stall you’re paid for into a breakout you’re capped on.
- Mind the term structure. You are selling front-month IV and buying back-month IV; the trade is better-paid when the front is rich relative to the back, as it often is ahead of scheduled events.
Risks
- A fast rally through the short strike caps the position while the back-month leg hasn’t fully converted to intrinsic value — the frustrating case where you were right on direction but too right, too fast.
- A decline loses the debit: below the long strike at the back expiration, the whole $1.60 can be gone.
- Vega risk on the back month: an IV collapse marks down the leg you own more than the leg you sold.
- Management at the front expiration is mandatory — the short call must be closed, rolled, or allowed to expire, and assignment risk rises as it goes in the money near the dividend.
FAQ
Diagonal vs calendar spread — what’s the difference?
A calendar spread uses the same strike in two expirations and profits purely from the front month decaying faster. A diagonal uses different strikes in two expirations, adding a directional bias: it wants the stock to move toward the short strike, not just sit still.
How do you pick diagonal strikes?
The short strike is a destination — place it where price can plausibly drift and then stall, which is what the Call Wall measures. The long strike sits at or below the current price; the deeper in the money you buy it, the more the trade behaves like stock with a call sold against it.
What is the max loss on a diagonal?
The net debit paid. Because the long option always has more time remaining than the short one, the short leg can never be worth more than the long leg at the front expiration, so the structure cannot lose more than its cost.
This article is for educational purposes only and is not financial advice. Options involve substantial risk and are not suitable for all investors.