A vertical spread is an options strategy that buys one option and sells another of the same type and expiration at a different strike, creating a position with defined maximum profit and defined maximum loss. “Vertical” refers to the strikes stacked above and below each other on an options chain. Every vertical is one of four structures — bull call, bear put, bull put, or bear call — and each expresses a directional view with risk that is capped on both sides from the moment the trade is opened.
Key Takeaways
- Two legs, same type (both calls or both puts), same expiration, different strikes — that is the entire recipe.
- Debit spreads pay money up front and profit when a move happens; credit spreads collect money and profit when a move fails to happen.
- Max loss is the debit paid (debit spreads) or the width minus the credit (credit spreads) — never more.
- The same risk graph can be built with calls or puts: a bull call spread and a bull put spread at the same strikes are economically near-identical twins.
How Vertical Spreads Work
The short leg is what separates a spread from a plain option. When you buy a call outright, you pay for unlimited upside, and the option’s extrinsic value bleeds away daily. Selling a second call above it hands some of that upside back to the market in exchange for cash — reducing your cost, your theta bill, and your exposure to an implied-volatility crush, all at once. The price of that relief is a ceiling on profit at the short strike.
The debit/credit distinction is about what you are being paid for. A debit spread pays for a directional move: you need price to travel toward the short strike to win. A credit spread collects premium for a move not happening: you win if price stays on your side of the short strike, including when the stock goes nowhere at all. That asymmetry — needing something to happen versus needing nothing to happen — is the real decision between the two, more than any difference in the risk graphs.
And the graphs themselves can be twins. Selling the 90/100 put spread produces nearly the same P&L profile as buying the 90/100 call spread, because of put-call parity. In practice traders choose based on which side is richer: credit spreads sell options, so they are often preferred when implied volatility is elevated, while debit spreads are favored when options are cheap.
Example
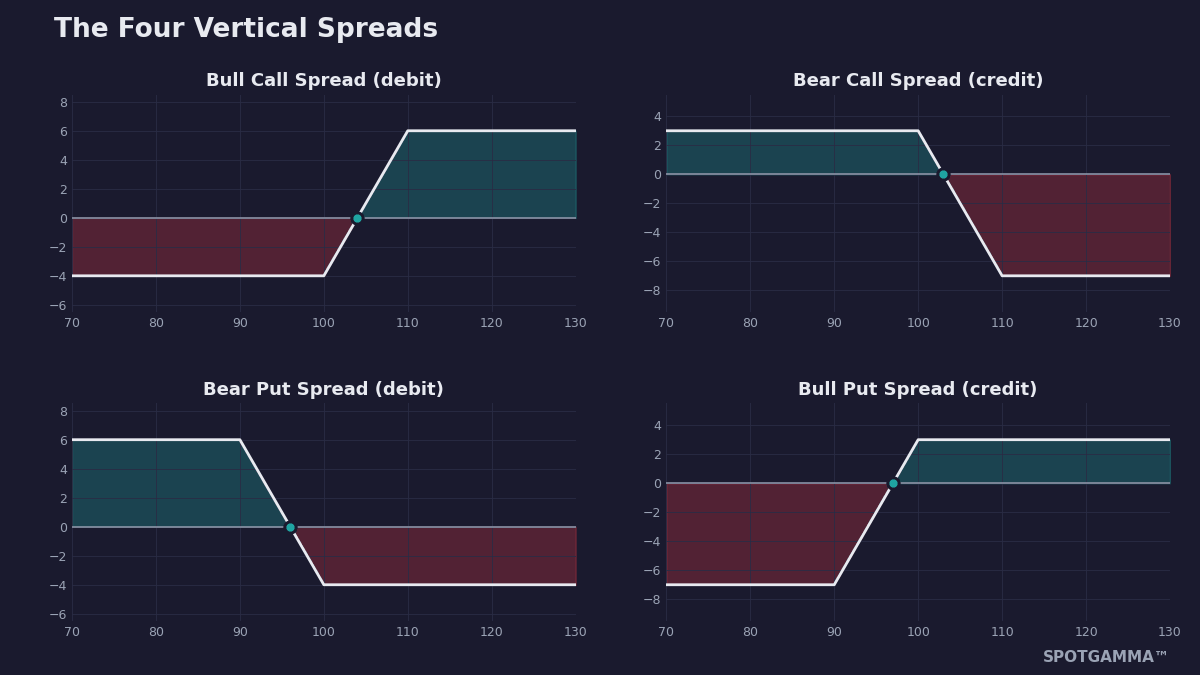
With the stock at $100, here is the full two-by-two — two directions, each built both ways:
- Bull call spread (debit): buy the 100 call, sell the 110 call for a $4.00 debit. Max profit $600 above 110; max loss $400 below 100; breakeven 104.
- Bear put spread (debit): buy the 100 put, sell the 90 put for a $4.00 debit. Max profit $600 below 90; max loss $400 above 100; breakeven 96.
- Bull put spread (credit): sell the 100 put, buy the 90 put for a $3.00 credit. Max profit $300 above 100; max loss $700 below 90; breakeven 97.
- Bear call spread (credit): sell the 100 call, buy the 110 call for a $3.00 credit. Max profit $300 below 100; max loss $700 above 110; breakeven 103.
Notice the trade-offs: the debit versions risk less and pay more but need the move; the credit versions win in more scenarios (including sideways) but risk more than they can make. Neither is “better” — they price the same uncertainty from opposite sides.
Vertical Spreads vs. One Another
Each of the four has its own deep-dive in our options strategy library:
- Bull call spread — the defined-risk way to buy a rally without paying full premium.
- Bear put spread — the same logic pointed down: paid downside exposure with a capped cost.
- Bull put spread — income from a floor holding; the building block of the iron condor’s lower half.
- Bear call spread — income from a ceiling holding, the classic rally-fading structure.
Using Positioning Data to Trade It Better
Verticals are the building block of defined-risk trading — and dealer positioning gives their strikes natural anchors:
- Debit spreads: target the next wall. The short strike is your profit target, so place it where price can realistically arrive and then stall — at or just inside the Call Wall or Put Wall, the strikes where dealer hedging has historically slowed moves. You are paid in full if price reaches the wall; you give up nothing beyond it.
- Credit spreads: sell beyond the wall. A credit spread is a bet that a move fails — so sell it past the level where hedging flows already resist that move. Checking the gamma exposure (GEX) regime tells you whether those levels are likely to hold (positive gamma) or break (negative gamma).
- Model all four before choosing. Build the debit and credit versions side by side in SpotGamma’s free Options Calculator and compare breakevens against the level map.
Risks
- Capped profit cuts both ways: a correct directional call through the short strike earns no more than the max, however far price runs.
- Credit spreads carry asymmetric payouts — in the examples, one full loss ($700) erases more than two full wins ($300 each).
- Pin risk at expiration: a stock settling at or near the short strike creates assignment uncertainty that can leave you with an unintended position.
- Spreads are less liquid than single options; crossing two bid/ask spreads carelessly can consume a meaningful share of the edge.
FAQ
What is the difference between a debit spread and a credit spread?
A debit spread pays cash up front and profits when price moves toward the short strike — you are buying a move. A credit spread collects cash up front and profits when price stays on your side of the short strike — you are selling someone else’s move. Risk is defined either way: the debit paid, or the width minus the credit.
Are vertical spreads better than buying options outright?
They solve different problems. A spread costs less, decays slower, and suffers less from IV crush, but caps the payoff; a long option keeps unlimited upside at the price of full premium and faster decay. Spreads tend to shine when options are expensive or when you have a specific price target rather than a view that a move could be enormous.
How do you choose vertical spread strikes?
Anchor them to levels rather than round numbers. For debit spreads, set the short strike at a realistic target such as the Call Wall or Put Wall, where dealer hedging has historically stalled price. For credit spreads, sell strikes beyond those walls so the market’s own friction stands between price and your risk.
This article is for educational purposes only and is not financial advice. Options involve substantial risk and are not suitable for all investors.