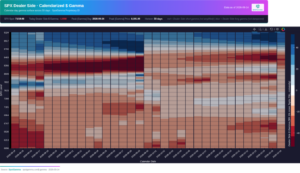
A 25bp hike is overwhelmingly expected on September 16, which makes the dot plot the real surprise vector. A look at what the options market is pricing, where the big volatility hedges are showing up, why September VIX settles before the decision, and why Friday’s expiration may be the bigger structural event.
bonds
Jackson Hole 2026: What the Options Market Expects
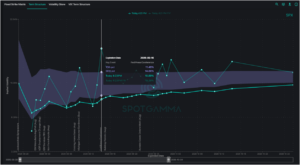
SPY forward IV prices Jackson Hole as a non-event, but CTAs are stretched short Treasuries and SPX gamma flips near 7780 — an asymmetric setup into Friday.
Credit Market Volatility vs. Equity Volatility
The following is an automated transcript of the video above, for your convenience. Please pardon any typos. Volatility Divergence Between Bonds and Equities Today we wanted to talk about volatility, and specifically the volatility divergence between bonds and equities. So on your screen we have the MOVE index, which is considered to be the bond […]