How VIX expiration dealer positioning likely capped the VIX near 20, and what three-month SPX put skew suggests about hedging demand into earnings.
VIX
Tech Dip, Not Broad Equity Selling: Brent Kochuba On tastylive
Why the tech selloff rotation left equal-weight indices steady, what VIX term structure and correlation show, and how short-dated call flies play a bounce.
Index Put Protection Is Cheap With 10-Year Treasury Bonds at 5.3%
SpotGamma founder Brent Kochuba joined tastylive to explain why index put protection stays cheap with the 10-year at 5.3% and bond volatility climbing.
The S&P500’s Diversification Problem
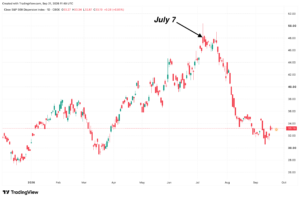
SpotGamma believes traders should add long exposure via NDX/QQQ calls due to a potential rally in equities through mid terms which would couple with a potential increase in volatility. Both higher equity prices and higher volatility benefit call positions.
We prefer the tech-heavy NDX vs SPX due to a “diversification drag” the S&P500 may experience.
FOMC Preview: The Hike Is Priced. The Dots Aren’t.
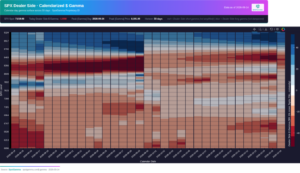
A 25bp hike is overwhelmingly expected on September 16, which makes the dot plot the real surprise vector. A look at what the options market is pricing, where the big volatility hedges are showing up, why September VIX settles before the decision, and why Friday’s expiration may be the bigger structural event.
Gamma Guy: S&P 500 Realized Volatility Is the Lowest Since 2020
Brent Kochuba, founder of SpotGamma, joined tastylive Tuesday to explain why S&P 500 realized volatility sits at 2020 lows ahead of FOMC and a huge OPEX.
CPI Is the Catalyst. 7600 Is the Trade.
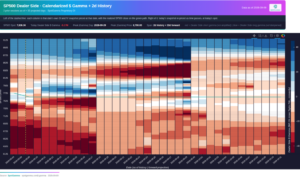
Markets are pricing a roughly 70% chance of a rate hike at the September 16 FOMC, and August CPI is the last inflation print the Fed sees before deciding. A look at what the option market is implying, the gamma setup into Friday’s expiration, and the three scenarios that matter.
The New Volatility Regime
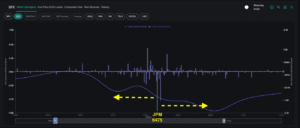
Over the past several weeks, we have consistently highlighted the market’s growing fragility. From the negative gamma “trapdoor” to the destabilizing impact of geopolitical shocks, the message has been clear: this is no longer a range-bound market. Last week confirmed those warnings, as the S&P 500 is down nearly 9% from all-time highs. On Thursday and Friday, traders […]
After OPEX: Market Loses Its Shock Absorber
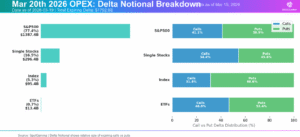
The options market has just cleared one of the largest structural events of the quarter, as Friday’s OPEX saw nearly $1.4 trillion in delta notional expire for the S&P 500. Because significant positions have now rolled off from the March expiration, the market has lost an important stabilizing force just as macro pressures begin to build. […]
VIX Expiration, Oil, and the JP Morgan Collar Trade: What’s Driving the S&P 500
Market Summary The market is entering a critical window where VIX expiration, quarterly options expiration, crude oil, and the JP Morgan collar trade are all colliding at once. The core argument is simple: implied volatility remains elevated while realized volatility has stayed unusually muted, and that mismatch may not last much longer. If oil continues […]