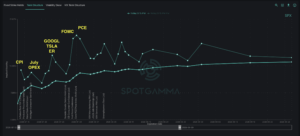
The S&P 500 spent early July grinding higher with sector rotation quietly forming beneath a calm index. As SPX price action remained relatively muted over the past week, implied volatility dropped to near-record lows as of Friday: IV for contracts expiring next week now sit in the 6-10% range. Regardless of any directional bias for […]
realized volatility
Stock & Bond Correlations: “No Crying in Correlation”
Alpha Exchange
Implied Volatility Reading in the SPX & VIX
Brent Kochuba, Founder of SpotGamma, joins Imran Lakha of Options-Insights to talk about the current volatility readings in the SPX and VIX. This covers both realized and implied volatility which are shifting ahead of a large options expiration.
Gamma vs Realized Volatility
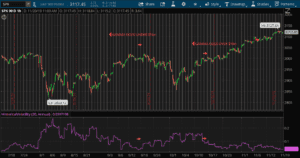
Gamma appears to give traders an edge in predicting market volatility. Here we show the last few months of historical volatility as a quick method to back up this point. Volatility does not imply a direction in the market, just expanded movement. Often this is correlated with market drops, but also rapid rises as seen […]