• Skip to main content
  • Skip to primary sidebar

SpotGamma™

S&P 500 Stock Market Gamma Trading Levels Based on Options Open Interest

  • About
  • Pricing
  • Academy
  • Resources
    • Tool Demos
    • Case Studies
    • Blog
    • Support Center
    • Daily Report
    • Free Trading Tools
      • Opening Setup Free Report
      • Options Profit Calculator
      • SPX Gamma Exposure
      • Implied Earnings Moves
    • Free Training
    • Report Card
  • Login

SpotGamma Weekly

Oct 04 2026

Surging Yields Create Risk — And Opportunity

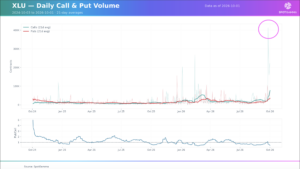
With 10-year treasury yields now at two-decade highs, the topic of rates has dominated markets. Rising rates adds meaningful stress to the economy at large — creating both risk and opportunity for traders. The market’s most rate-sensitive corners have taken the brunt of the damage. Small caps (IWM), utilities (XLU), homebuilders (ITB), and industrials (XLI) […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: Bond Volatility, Call Volume, dealer gamma, Gamma Exposure, implied volatility, options positioning, options skew, Rate-Sensitive Sectors, spotgamma weekly, tlt calls, Utilities Stocks, VST options, XLU calls

Sep 27 2026

META Rewrites the AI Trade

Meta’s new Muse AI Agent has done what a year of capex headlines could not: it has convinced the market that the company’s $200 billion investment in AI has a consumer-facing payoff. META rallied 13% over the past week and pushed toward 52-week highs as the personal agent app topped the download charts. The enthusiasm […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, Gamma Exposure, implied volatility, META call spread, META implied volatility, Meta Muse AI agent, META options, Options Calculator, options positioning, options skew, spotgamma weekly

Sep 20 2026

Quiet Oil Options Mask Tail Risk

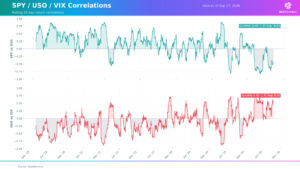
Dual line charts of rolling 20-day return correlations for SPY vs USO and USO vs VIX from 2019 to 2026.

Oil prices drove headlines this past week amidst flare-ups in the ongoing Iran conflict. WTI crude broke above $100 on September 15, and diesel fuel hit an all-time high of $6.31 per gallon. The mystery is that despite the price spike, the options market for oil remains unusually subdued. The CBOE Crude Oil Volatility Index […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: COP options, CVX options, dealer gamma, Gamma Exposure, implied volatility, oil options, oil refiners, oil shorts, Options Calculator, options positioning, options skew, OVX, spotgamma weekly, USO puts, XOM options

Sep 13 2026

Hedging Against a Volatility Spike: VIX Calls vs. SPX Puts
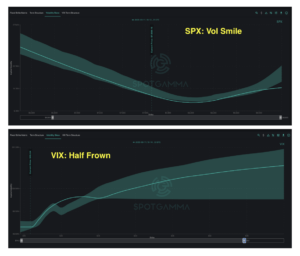
Two SpotGamma charts show SPX vol smile and VIX half frown of implied volatility versus strike.

A series of major market catalysts arrive next week: the FOMC rate decision, VIX Expiration, and September Triple Witching OPEX. Options positioning suggests that institutions are already paying up for event protection. Over the past two weeks, we have observed notable VIX hedging activity in our daily FlowPatrol reports. This included several particularly significant positions: […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, Gamma Exposure, implied volatility, Options Calculator, options positioning, options skew, spotgamma weekly, SPX puts, theta decay, Triple Witching OPEX, VIX calls, Volatility Skew

Sep 07 2026

AI Infrastructure Runs Hot into September
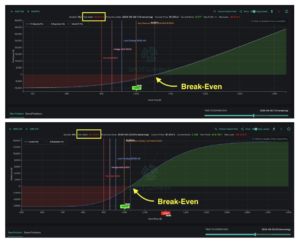
Two profit/loss charts for MU stock showing break-even points around $1,000 strike with expiration on 2026-09-29.

August closed with robust corporate earnings, and nowhere was that clearer than in the AI trade stocks. Last week’s standout report came from Dell (DELL), which jumped 16% after beating estimates and raising guidance. Dell is a leading server provider for AI data center infrastructure. Its results echoed what Nvidia (NVDA) showed a week earlier: […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: AI data center stocks, bull call spread, call skew, dealer gamma, DELL earnings, Gamma Exposure, implied volatility, Options Calculator, options positioning, options skew, semiconductor rotation, spotgamma weekly, theta decay

Aug 30 2026

Software Earnings Reignite Risk Appetite
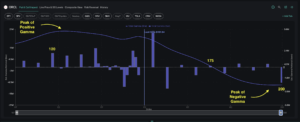
SPY options gamma chart showing strike levels 120, 175, and 200 with positive and negative gamma peaks.

Market sentiment was mixed last week following NVDA earnings and Jackson Hole. While NVDA’s solid outlook pushed the market to within inches of all-time highs, Warsh’s hawkish tone seemed to increase the probability of a September rate hike. Throughout August, the S&P 500 has closed in a narrow 2.6% band (SPX 7,600 – 7,800). The […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: contango, CRM earnings, dealer gamma, forward implied volatility, Gamma Exposure, implied volatility, options positioning, options skew, ORCL options, semiconductor rotation, spotgamma weekly, SPX term structure, synthetic gamma

Aug 23 2026

Volatility Has Compressed. What Happens Next?
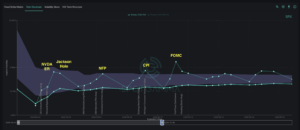
SPX term structure chart showing implied volatility declining from 32% to 10% across expiration dates through October 2026.

The S&P 500 pulled back slightly last week, and the market’s recent volatility compression phase appears ready for a reset. With earnings season largely over, both index and single stock volatility have dropped from the elevated levels that prevailed earlier this summer. Our pre-market Founder’s Note on Friday explained how substantial short-options positions cleared with […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: contango, dealer gamma, forward implied volatility, Gamma Exposure, implied volatility, IWM put skew, Jackson Hole, Kevin Warsh, options positioning, options skew, QQQ call skew, spotgamma weekly, SPX term structure, synthetic gamma

Aug 16 2026

How Traders Can Play Low Volatility Environments
SPX options payoff diagram showing profit/loss curves with key strike levels and walls marked between $7,500-$8,000.

The S&P 500 has spent much of the summer grinding steadily higher to achieve record highs. Meanwhile, implied volatility has reset toward yearly lows for both major indices and many single stocks. When options become this cheap, the price of volatility itself can open new trading opportunities. The Term Structure chart reveals current SPX at-the-money […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call spreads, contango, dealer gamma, Gamma Exposure, implied volatility, long straddle, low implied volatility strategies, options convexity, options positioning, options skew, spotgamma weekly, SPX term structure, synthetic gamma, theta decay

Aug 09 2026

Welcome to the Summer Melt-Up

DRAM options gamma chart showing total gamma curve, call/put gamma bars, and volatility points at $45 and $61.5.

The S&P 500 delivered a high octane four-day run last week, establishing all-time highs with a 6% rise from weekly lows. Shifting interest rate expectations, easing Middle East tensions, and strong corporate earnings powered the dramatic rally. The sharp surge brought out notable divergences across the tech space. Software outperformed the broader market, with strong […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, dram ETF, dram options, Gamma Exposure, implied volatility, options positioning, options skew, realized volatility, SanDisk stock, semiconductor stocks, spotgamma weekly, synthetic gamma

Aug 02 2026

The New Normal in Volatility Takes Shape
Options implied volatility skew tables for SNDK and SMH showing strike prices and expiration dates through September 2026.

The final week of July proved to be quite dramatic. An FOMC decision, PCE inflation data, and the Super Bowl of Q2 earnings all took place over the span of just 2 days, with companies representing 36% of the S&P 500 by weight reporting results last week. The results were extreme: U.S. 30-year treasury yields […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: AI trade unwind, collar strategy, dealer gamma, earnings implied move, implied volatility, options positioning, semiconductor stocks, semiconductor volatility, SNDK options, SNDK volatility, SPCX earnings, SPCX lockup, spotgamma weekly

  • Go to page 1
  • Go to page 2
  • Go to page 3
  • Interim pages omitted …
  • Go to page 7
  • Go to Next Page »

Primary Sidebar

SpotGamma-Subscriber-Signup-Banner

  • DKS Insiders Are Buying the Earnings Dip — Including a $1M CFO Purchase
  • Surging Yields Create Risk — And Opportunity
  • Index Put Protection Is Cheap With 10-Year Treasury Bonds at 5.3%
  • Friday Jobs Report Preview: What the Market Wants to See
  • Micron Earnings Preview: Can the AI Memory Boom Keep Delivering?
  • youtube
  • x
  • Privacy Policy
  • Disclaimer
  • Terms & Conditions
  • Support Center
  • Media
  • Contact Us

©2026 TenTen Capital LLC DBA SpotGamma

All SpotGamma materials, information, and presentations are for educational purposes only and should not be considered specific investment advice nor recommendations. Futures, foreign currency and options trading contains substantial risk and is not for every investor. An investor could potentially lose all or more than the initial investment. Risk capital is money that can be lost without jeopardizing one's financial security or lifestyle. Only risk capital should be used for trading and only those with sufficient risk capital should consider trading. Past performance is not necessarily indicative of future results. Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.

View Full Risk Disclosure