• Skip to main content
  • Skip to primary sidebar

SpotGamma™

S&P 500 Stock Market Gamma Trading Levels Based on Options Open Interest

  • About
  • Pricing
  • Academy
  • Resources
    • Tool Demos
    • Case Studies
    • Blog
    • Support Center
    • Daily Report
    • Free Trading Tools
      • Opening Setup Free Report
      • Options Profit Calculator
      • SPX Gamma Exposure
      • Implied Earnings Moves
    • Free Training
    • Report Card
  • Login

OPEX

Jun 14 2026

Triple Witching + FOMC Fuels Volatility Risk

SPX term structure chart showing implied volatility and settlement levels from June to August 2026 with downward trend arrows.

The market delivered several volatile sessions last week as traders navigated Wednesday’s CPI inflation report, Friday’s massive SpaceX IPO (SPCX), and a mix of Iran-driven headlines throughout. Last Sunday, we wrote about how extreme options positioning into major catalysts could spark the exact volatile market behavior observed over the past several days. Tuesday’s wild 200-point […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer hedging, FOMC, Gamma Exposure, gold GLD outlook, implied volatility, Kevin Warsh Fed, market makers, negative gamma, OPEX, spotgamma weekly, SPX term structure, triple witching

Apr 19 2026

The Hidden Mechanics Behind Last Week’s Rally
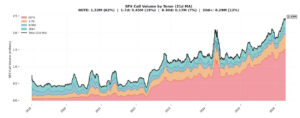
Stacked area chart showing SPX call volume by expiration tenor from 2019 to 2026, with total volume reaching 2.43 million contracts.

The S&P 500 has bounced back to record highs, closing decisively above 7,100 after Friday’s 1.2% rally. That marks a 12% rise from March lows in just under three weeks. In that same timeframe, volatility expectations have seemingly collapsed: VIX is down 40% since March 31, dropping from >30 to below 18. Crude oil has […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call buying, call options, dealer gamma, dealer positioning, geopolitical risk, implied vol, iv, OPEX, rv, spotgamma weekly, SPX, volatility

Apr 12 2026

Vol Crush Lifts the S&P 500 — Will the Rally Last?
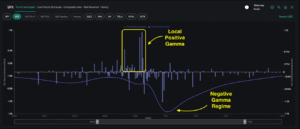
SPX gamma chart showing positive gamma peak near 6820 and negative gamma regime below 7020.

Following last week’s ceasefire announcement, the S&P 500 lifted 3% from roughly 6,550 to 6,800. On the surface, this rally looked like a meaningful shift toward risk-on sentiment as implied volatility collapsed rapidly across all expirations. Similarly, VIX plummeted below 20 for the first time in four weeks, marking one of its largest single-day declines ever. Yet […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, dealer positioning, geopolitical risk, implied vol, iv, negative gamma, OPEX, spotgamma weekly, SPX, vanna, vol crush, volatility

Apr 05 2026

How One Key Level Drove Last Week’s Rally
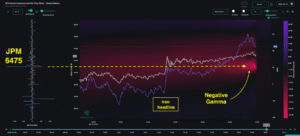
SPX gamma exposure and net OI chart showing price movement with negative gamma spike and Iran headline event on Mar 31, 2026.

The S&P 500 bounced back 2% last week after scraping against 6-month lows. Mixed headlines on the Iran conflict explained much of this tug-of-war, yet markets are still holding their breath. For many traders, the rally felt counterintuitive: How can equities rally so furiously if geopolitical uncertainties remain unresolved? When looking at Tuesday’s major bounce in […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, dealer positioning, FOMC, geopolitical risk, implied vol, iv, JPM Collar, negative gamma, OPEX, put skew, realized vol, spotgamma weekly, SPX, trace, volatility

Mar 22 2026

After OPEX: Market Loses Its Shock Absorber
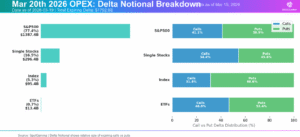
Stacked bar charts showing March 20, 2026 OPEX delta notional breakdown by asset class, with calls vs puts distribution percentages.

The options market has just cleared one of the largest structural events of the quarter, as Friday’s OPEX saw nearly $1.4 trillion in delta notional expire for the S&P 500. Because significant positions have now rolled off from the March expiration, the market has lost an important stabilizing force just as macro pressures begin to build. […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, dealer positioning, FOMC, geopolitical risk, implied vol, iv, negative gamma, OPEX, put skew, realized vol, spotgamma weekly, SPX, trace, VIX, volatility, Volatility Skew

Mar 22 2026

VIX Expiration, Oil, and the JP Morgan Collar Trade: What’s Driving the S&P 500

Market Summary The market is entering a critical window where VIX expiration, quarterly options expiration, crude oil, and the JP Morgan collar trade are all colliding at once. The core argument is simple: implied volatility remains elevated while realized volatility has stayed unusually muted, and that mismatch may not last much longer. If oil continues […]

Written by SpotGamma · Categorized: Market Analysis · Tagged: Iran, JPM Collar, oil, OPEX, Stock Market Crash, VIX, volatility

Feb 22 2026

Right Tail Risk Is Building in the S&P 500
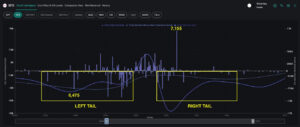
S&P 500 options gamma chart showing left and right tail risk zones with strike prices and gamma levels.

The market spent most of last week locked in the SPX 6,800–6,900 range that has largely held since Thanksgiving. Wednesday’s VIX expiration and Friday’s monthly OPEX defined the week’s rhythm, while negative gamma positioning and elevated single-stock put demand maintained pressure under the surface. Our historical OPEX data suggests the market is positioned for a […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: Compass, dealer gamma, dealer positioning, iv, mag7, negative gamma, OPEX, positive gamma, spotgamma weekly, SPX, Synthetic OI, volatility

Feb 15 2026

Flat Index Masks Hidden Chaos

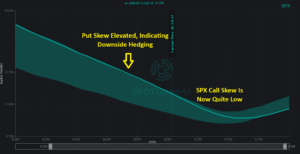
SPX put skew chart showing elevated downside hedging with call skew at low levels as of February 13, 2026.

Overall price stability in the S&P 500 is masking one of the most unusual equity environments in recent years. While SPX has been roughly flat over the past month, the average constituent has moved 10.8% — a 99th percentile dispersion reading, as we discussed in our Thursday AM Founder’s Note. All signs point to increasing fragmentation beneath […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: FOMC, iv, OPEX, positive gamma, spotgamma weekly, SPX, VIX, volatility

Feb 08 2026

The Market’s 0DTE Underbelly Is Exposed
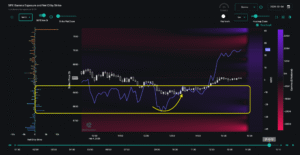
SPX options data showing strike prices, net open interest, and gamma exposure throughout trading hours on Feb 4, 2026.

Last week reminded us just how fast market stability can give way to volatility. After trading near all-time highs at 7,000, the S&P 500 fell 3% in just three sessions, closing Thursday at 6,798 amid weakness in software and crypto. Our last Sunday Newsletter focused specifically on how this type of fragility underscores today’s market. This […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: FOMC, iv, OPEX, positive gamma, spotgamma weekly, SPX, VIX, volatility

Feb 01 2026

SPX Touches 7,000 and Cracks — What Makes This Market So Fragile?
Chart showing cumulative dealer gamma (positive) and non-Odte dealer gamma (negative) across strike prices, with bars indicating gamma levels.

Market Fragility in the Face of All-Time Highs As the S&P 500 pushes record highs, the options market continues to flash warning signals beneath the surface. Underlying risk from volatility discrepancies and index-equity correlation suggest an environment prone to vol spasms — similar to what we witnessed with Thursday’s (1/29) sharp selloff and reversal. These […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: FOMC, iv, OPEX, positive gamma, spotgamma weekly, SPX, VIX, volatility

  • « Go to Previous Page
  • Go to page 1
  • Go to page 2
  • Go to page 3
  • Go to page 4
  • Interim pages omitted …
  • Go to page 6
  • Go to Next Page »

Primary Sidebar

SpotGamma-Subscriber-Signup-Banner

  • META Earnings Preview: Will Volatility Outrun the Options Market?
  • Traders Are Bidding The Put Wing Without Paying For Vol: Brent Kochuba On tastylive
  • Tesla & SpaceX Earnings Preview: Two Reports, One Merger Question — What Are Options Pricing?
  • Tech Dip, Not Broad Equity Selling: Brent Kochuba On tastylive
  • GameStop (GME): Nearly $100M in Insider Buying Meets Elevated Options Volatility
  • youtube
  • x
  • Privacy Policy
  • Disclaimer
  • Terms & Conditions
  • Support Center
  • Media
  • Contact Us

©2026 TenTen Capital LLC DBA SpotGamma

All SpotGamma materials, information, and presentations are for educational purposes only and should not be considered specific investment advice nor recommendations. Futures, foreign currency and options trading contains substantial risk and is not for every investor. An investor could potentially lose all or more than the initial investment. Risk capital is money that can be lost without jeopardizing one's financial security or lifestyle. Only risk capital should be used for trading and only those with sufficient risk capital should consider trading. Past performance is not necessarily indicative of future results. Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.

View Full Risk Disclosure