• Skip to main content
  • Skip to primary sidebar

SpotGamma™

S&P 500 Stock Market Gamma Trading Levels Based on Options Open Interest

  • About
  • Pricing
  • Academy
  • Resources
    • Tool Demos
    • Case Studies
    • Blog
    • Support Center
    • Daily Report
    • Free Trading Tools
      • Opening Setup Free Report
      • Options Profit Calculator
      • SPX Gamma Exposure
      • Implied Earnings Moves
    • Free Training
    • Report Card
  • Login

implied volatility

Sep 20 2026

Quiet Oil Options Mask Tail Risk

Dual line charts of rolling 20-day return correlations for SPY vs USO and USO vs VIX from 2019 to 2026.

Oil prices drove headlines this past week amidst flare-ups in the ongoing Iran conflict. WTI crude broke above $100 on September 15, and diesel fuel hit an all-time high of $6.31 per gallon. The mystery is that despite the price spike, the options market for oil remains unusually subdued. The CBOE Crude Oil Volatility Index […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: COP options, CVX options, dealer gamma, Gamma Exposure, implied volatility, oil options, oil refiners, oil shorts, Options Calculator, options positioning, options skew, OVX, spotgamma weekly, USO puts, XOM options

Sep 18 2026

Celsius Insiders Are Buying the Dip — And Options Are Cheap Into the Catalyst
Celsius Insiders Are Buying the Dip — And Options Are Cheap Into the Catalyst

Three CELH insiders bought roughly $1.8 million of stock on the open market within six days in mid-September, one of them paying above the close. A look at why they bought when they did, and why the options market has not repriced for any of it into the November 5 print.

Written by SpotGamma · Categorized: Market Analysis · Tagged: CELH, implied volatility, insider buying, IV Rank, negative gamma, open interest, skew, volatility

Sep 17 2026

Trump Xi Summit and the Market Outlook
Trump–Xi Summit: What Markets Are Watching on September 24

President Trump hosts Xi Jinping on September 24, days after the Fed’s first rate hike since 2023. Tariffs, rare earths, chip policy and Taiwan are all in play — and SpotGamma’s Compass shows cheap implied volatility across several China-sensitive names.

Written by SpotGamma · Categorized: Market Analysis · Tagged: china, gamma, implied volatility, retail stocks, risk reversal, tariffs, volatility

Sep 15 2026

FOMC Preview: The Hike Is Priced. The Dots Aren’t.
FOMC Preview: The Hike Is Priced. The Dots Aren't.

A 25bp hike is overwhelmingly expected on September 16, which makes the dot plot the real surprise vector. A look at what the options market is pricing, where the big volatility hedges are showing up, why September VIX settles before the decision, and why Friday’s expiration may be the bigger structural event.

Written by SpotGamma · Categorized: Market Analysis · Tagged: bonds, FOMC, gamma, implied volatility, interest rates, OPEX, SPX, VIX, volatility

Sep 15 2026

Gamma Guy: S&P 500 Realized Volatility Is the Lowest Since 2020
Gamma Guy: S&P 500 Realized Volatility Is the Lowest Since 2020

Brent Kochuba, founder of SpotGamma, joined tastylive Tuesday to explain why S&P 500 realized volatility sits at 2020 lows ahead of FOMC and a huge OPEX.

Written by SpotGamma · Categorized: Market Analysis · Tagged: 0DTE, FOMC, implied volatility, NDX, negative gamma, OPEX, realized volatility, SPX, tastylive, VIX

Sep 13 2026

Hedging Against a Volatility Spike: VIX Calls vs. SPX Puts
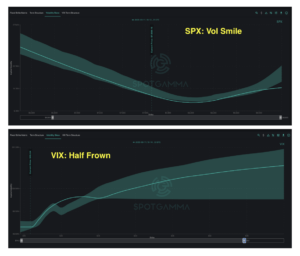
Two SpotGamma charts show SPX vol smile and VIX half frown of implied volatility versus strike.

A series of major market catalysts arrive next week: the FOMC rate decision, VIX Expiration, and September Triple Witching OPEX. Options positioning suggests that institutions are already paying up for event protection. Over the past two weeks, we have observed notable VIX hedging activity in our daily FlowPatrol reports. This included several particularly significant positions: […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, Gamma Exposure, implied volatility, Options Calculator, options positioning, options skew, spotgamma weekly, SPX puts, theta decay, Triple Witching OPEX, VIX calls, Volatility Skew

Sep 12 2026

September OPEX Options Positioning: Why 7,600 Is the Line | The OPEX Effect
September OPEX Options Positioning: Why 7,600 Is the Line | The OPEX Effect

Brent Kochuba of SpotGamma joined Excess Returns Thursday on September OPEX options positioning, the 7,600 gamma line, oil-rate risk and cheap tech vol.

Written by SpotGamma · Categorized: Market Analysis · Tagged: correlation, dealer hedging, Excess Returns, implied volatility, negative gamma, OPEX, SMH, SPX, The OPEX Effect

Sep 10 2026

S&P 500 Negative Gamma Below 7,600 — Brent Kochuba on tastylive
S&P 500 Negative Gamma Below 7,600 Meets Vol With Room to Lift

Brent Kochuba, founder of SpotGamma, joined tastylive Thursday to map S&P 500 negative gamma below 7,600, a lifting vol surface and Oracle’s call skew.

Written by SpotGamma · Categorized: Market Analysis · Tagged: 0DTE, dealer hedging, earnings, implied volatility, IWM, negative gamma, ORCL, SPX, tastylive

Sep 09 2026

Gamma Guy with tastylive: Options Positioning Pins the Index While Tech Names Make Moves
Gamma Guy: September OPEX Positioning Pins the Index While Tech Moves

Brent Kochuba, founder of SpotGamma, broke down September OPEX positioning, 0DTE flows and cheap IWM hedges on tastylive Tuesday, September 8.

Written by SpotGamma · Categorized: Market Analysis · Tagged: 0DTE, AAPL, dealer gamma, dispersion, implied volatility, IWM, OPEX, SPX, tastylive

Sep 07 2026

AI Infrastructure Runs Hot into September
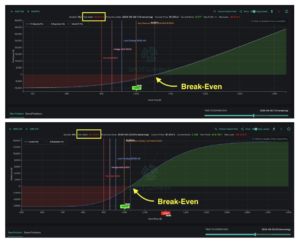
Two profit/loss charts for MU stock showing break-even points around $1,000 strike with expiration on 2026-09-29.

August closed with robust corporate earnings, and nowhere was that clearer than in the AI trade stocks. Last week’s standout report came from Dell (DELL), which jumped 16% after beating estimates and raising guidance. Dell is a leading server provider for AI data center infrastructure. Its results echoed what Nvidia (NVDA) showed a week earlier: […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: AI data center stocks, bull call spread, call skew, dealer gamma, DELL earnings, Gamma Exposure, implied volatility, Options Calculator, options positioning, options skew, semiconductor rotation, spotgamma weekly, theta decay

  • « Go to Previous Page
  • Go to page 1
  • Go to page 2
  • Go to page 3
  • Go to page 4
  • Go to page 5
  • Go to page 6
  • Go to Next Page »

Primary Sidebar

SpotGamma-Subscriber-Signup-Banner

  • APLD: $6.7 Million in Insider Buying Meets a Key Gamma Inflection
  • Dip Buyers Step into the AI Unwind
  • Rising Correlation Is Thinning Out The Rotation Trade
  • Tech Selloff Looks Like Rotation: Brent Kochuba on Schwab Network
  • META Earnings Preview: Will Volatility Outrun the Options Market?
  • youtube
  • x
  • Privacy Policy
  • Disclaimer
  • Terms & Conditions
  • Support Center
  • Media
  • Contact Us

©2026 TenTen Capital LLC DBA SpotGamma

All SpotGamma materials, information, and presentations are for educational purposes only and should not be considered specific investment advice nor recommendations. Futures, foreign currency and options trading contains substantial risk and is not for every investor. An investor could potentially lose all or more than the initial investment. Risk capital is money that can be lost without jeopardizing one's financial security or lifestyle. Only risk capital should be used for trading and only those with sufficient risk capital should consider trading. Past performance is not necessarily indicative of future results. Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.

View Full Risk Disclosure