• Skip to main content
  • Skip to primary sidebar

SpotGamma™

S&P 500 Stock Market Gamma Trading Levels Based on Options Open Interest

  • About
  • Pricing
  • Academy
  • Resources
    • Tool Demos
    • Case Studies
    • Blog
    • Support Center
    • Free Daily Report
    • Free Trading Tools
      • Options Profit Calculator
      • SPX Gamma Exposure
      • Implied Earnings Moves
      • Volatility Ranking
    • Free Training
    • Report Card
  • Login

SpotGamma Weekly

Jul 05 2026

Passing the Baton: From Semis to Software?

Scatter plot showing call and put skew percentiles for various stock tickers, with a highlighted cluster on the left side.

The AI trade has been the story of the first half of 2026, and semiconductors have been the main characters. The sector now accounts for roughly 20% of the entire S&P 500 — a historically high concentration. As we covered in our previous newsletter, any meaningful profit-taking in this area brings up the important question […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call skew, call spread strategy, earnings volatility, implied volatility, IV Rank, market makers, market volatility, options positioning, options trading, sector rotation, ServiceNow options, software stocks, SpotGamma Compass, spotgamma weekly, Volatility Skew

Jun 28 2026

July’s Setup: Rotation and Repositioning
SPX volatility skew chart showing implied volatility curve across strike prices with current price level marked.

June lived up to its reputation as a volatile month with last week’s market drawdown. As we turn the page into July, the market now appears to be recalibrating positioning. Recent turbulence has driven capital rotation out of crowded tech leadership, and we now look for opportunities in alternative pockets of the market. In our […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: Convexity, COR1M, forward-implied volatility, implied volatility, JPM Collar roll, market makers, market volatility, options positioning, options trading, SpotGamma Compass, spotgamma weekly, SPX gamma, SPX term structure, Volatility Skew

Jun 21 2026

Vol Sellers Shrug off a Hawkish Fed

Line chart tracking SPX implied volatility across multiple expiration dates from June through August 2026, showing volatility decline over time.

Despite a hawkish Fed rattling equities midweek, the market easily and quickly retraced any lost ground by Thursday. With June OPEX now behind us and implied volatility reset toward recent lows, there is a soft feeling of “what’s next?” for the S&P 500 until earnings season ramps up next month. The June FOMC meeting on […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer hedging, FOMC, Gamma Exposure, hawkish Fed, implied volatility, JPM Collar roll, Kevin Warsh Fed, market makers, Micron earnings implied move, negative gamma, OPEX, SPCX options, spotgamma weekly, SPX term structure

Jun 14 2026

Triple Witching + FOMC Fuels Volatility Risk
SPX term structure chart showing implied volatility and settlement levels from June to August 2026 with downward trend arrows.

The market delivered several volatile sessions last week as traders navigated Wednesday’s CPI inflation report, Friday’s massive SpaceX IPO (SPCX), and a mix of Iran-driven headlines throughout. Last Sunday, we wrote about how extreme options positioning into major catalysts could spark the exact volatile market behavior observed over the past several days. Tuesday’s wild 200-point […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer hedging, FOMC, Gamma Exposure, gold GLD outlook, implied volatility, Kevin Warsh Fed, market makers, negative gamma, OPEX, spotgamma weekly, SPX term structure, triple witching

Jun 07 2026

The AI Trade Unwinds

Total gamma bar chart with line showing peak negative gamma around 545 strike and positive gamma spike of 610 at higher strike levels.

Wall Street’s historic weekly winning streak came to an abrupt halt last week. On Friday, a sharp NFP report drove the S&P 500 down over 2.6%, leading to a sharp AI selloff and rising bond yields. Adding fuel to the fire, the market now appears to be pricing in a rate hike by the end […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: AI trade unwind, dealer gamma, dealer hedging, Gamma Exposure, HIRO options flow, implied volatility, market makers, positive gamma, semiconductor selloff, SMH dealer gamma, spotgamma weekly, SPX options positioning, SPX term structure, volatility spasm

May 31 2026

June Catalysts Threaten a Volatility Spasm — How Are Traders Positioning?
Heatmap comparing IV rank versus skew rank for top 25 S&P 500 and Nasdaq-100 stocks as of May 29, 2026.

The S&P 500 has posted fresh record highs for the ninth straight week. Tech and semiconductor earnings fueled much of the recent surge, with SNOW climbing 52%, DELL gaining 57%, and MU surging 28% within one week. As we move into June, stretched positioning now meets a cluster of major catalysts. Three upcoming events will […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call skew, COR1M, dealer gamma, dealer hedging, dispersion risk, Gamma Exposure, implied volatility, June OPEX, market makers, positive gamma, put diagonal, spotgamma weekly, SPX options positioning, SPX term structure, volatility spasm

May 25 2026

Record Highs and Thinning Hedges

SPX implied volatility term structure chart showing economic events from May to July 2026, with peaks at PCE, NFP, CPI, and FOMC dates.

Last week, the S&P 500 closed its eighth straight weekly gain — the longest streak since 2023. As the rally continues to achieve record highs, underlying options positioning has evolved meaningfully since March. Most importantly, the market has quietly shed much of the protective hedging that was in place just two months ago. A dense […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call options, call skew, dealer gamma, dealer hedging, Gamma Exposure, implied volatility, market makers, risk reversal, spotgamma weekly, SPX options positioning, SPX term structure

May 17 2026

NVDA earnings vs. a stretched S&P 500

Volatility skew chart for NVDA showing call skew above the 90-day range with implied volatility on the y-axis and strike price on the x-axis.

For the fourth consecutive week, the S&P 500 has struck records highs. This week’s breach of SPX 7,500 even arrived in the face of hotter-than-expected CPI and PPI prints — data that historically would have triggered a meaningful selloff. The tone shifted somewhat on Friday, as the rally lost steam into monthly OPEX. The week […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call options, dealer gamma, dealer hedging, Gamma Exposure, implied vol, market makers, May OPEX 2026, NVDA earnings, NVDA implied move, options market analysis, options volatility skew, semiconductor stocks, spotgamma weekly, SPY put butterfly, tail hedge options

May 10 2026

The AI Trade Roars — But for How Long?
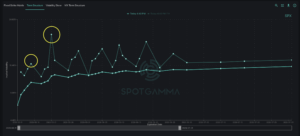
SPX term structure chart showing implied volatility curves from May to July 2026 with two circled peaks.

Last week, strong earnings pushed both the S&P 500 and Nasdaq to — once again — achieve all-time highs. Through the fast and furious AI-driven rally of the past 6 weeks, SPX has climbed 15% while NDX has surged 28%. The market’s pace of advance is well beyond historical norms, reflecting an exceptionally aggressive repositioning […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: 0DTE options, call options, dealer gamma, dealer hedging, earnings, Gamma Exposure, implied vol, market makers, May OPEX 2026, options market analysis, semiconductor stocks, spotgamma weekly, SPX options, VIX expiration, volatility

May 03 2026

Quiet Indices, Roaring Stocks: the Volatility Dispersion Trade
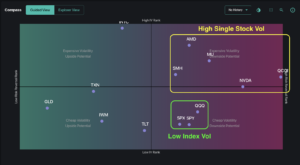
Four-quadrant scatter plot comparing IV rank and volatility levels across stocks and indices, with AMD, NVDA, and QQQ highlighted.

Robust Mag7 and semiconductor earnings have reinforced investor confidence in the AI trade, lifting the S&P 500 and Nasdaq to fresh highs. Index implied volatility (IV) — the options market’s expectation of future price movement — reset to its lowest level in three months. Despite the backdrop of the Iran conflict and heightened oil prices, […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: 0DTE options, call options, dealer gamma, implied vol, iron condor, options flow, semiconductor stocks, spotgamma weekly, SPX options, unusual options activity, volatility, volatility dispersion

  • « Go to Previous Page
  • Go to page 1
  • Go to page 2
  • Go to page 3
  • Go to page 4
  • Interim pages omitted …
  • Go to page 6
  • Go to Next Page »

Primary Sidebar

SpotGamma-Subscriber-Signup-Banner

  • Hedging Against a Volatility Spike: VIX Calls vs. SPX Puts
  • September OPEX Options Positioning: Why 7,600 Is the Line | The OPEX Effect
  • S&P 500 Negative Gamma Below 7,600 — Brent Kochuba on tastylive
  • CPI Is the Catalyst. 7600 Is the Trade.
  • Trade Idea Generation Using Opening Setup
  • youtube
  • x
  • Privacy Policy
  • Disclaimer
  • Terms & Conditions
  • Support Center
  • Media
  • Contact Us

©2026 TenTen Capital LLC DBA SpotGamma

All SpotGamma materials, information, and presentations are for educational purposes only and should not be considered specific investment advice nor recommendations. Futures, foreign currency and options trading contains substantial risk and is not for every investor. An investor could potentially lose all or more than the initial investment. Risk capital is money that can be lost without jeopardizing one's financial security or lifestyle. Only risk capital should be used for trading and only those with sufficient risk capital should consider trading. Past performance is not necessarily indicative of future results. Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.

View Full Risk Disclosure