• Skip to main content
  • Skip to primary sidebar

SpotGamma™

S&P 500 Stock Market Gamma Trading Levels Based on Options Open Interest

  • About
  • Pricing
  • Academy
  • Resources
    • Tool Demos
    • Case Studies
    • Blog
    • Support Center
    • Daily Report
    • Free Trading Tools
      • Opening Setup Free Report
      • Options Profit Calculator
      • SPX Gamma Exposure
      • Implied Earnings Moves
    • Free Training
    • Report Card
  • Login

dealer gamma

Jun 07 2026

The AI Trade Unwinds

Total gamma bar chart with line showing peak negative gamma around 545 strike and positive gamma spike of 610 at higher strike levels.

Wall Street’s historic weekly winning streak came to an abrupt halt last week. On Friday, a sharp NFP report drove the S&P 500 down over 2.6%, leading to a sharp AI selloff and rising bond yields. Adding fuel to the fire, the market now appears to be pricing in a rate hike by the end […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: AI trade unwind, dealer gamma, dealer hedging, Gamma Exposure, HIRO options flow, implied volatility, market makers, positive gamma, semiconductor selloff, SMH dealer gamma, spotgamma weekly, SPX options positioning, SPX term structure, volatility spasm

May 31 2026

June Catalysts Threaten a Volatility Spasm — How Are Traders Positioning?
Heatmap comparing IV rank versus skew rank for top 25 S&P 500 and Nasdaq-100 stocks as of May 29, 2026.

The S&P 500 has posted fresh record highs for the ninth straight week. Tech and semiconductor earnings fueled much of the recent surge, with SNOW climbing 52%, DELL gaining 57%, and MU surging 28% within one week. As we move into June, stretched positioning now meets a cluster of major catalysts. Three upcoming events will […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call skew, COR1M, dealer gamma, dealer hedging, dispersion risk, Gamma Exposure, implied volatility, June OPEX, market makers, positive gamma, put diagonal, spotgamma weekly, SPX options positioning, SPX term structure, volatility spasm

May 25 2026

Record Highs and Thinning Hedges

SPX implied volatility term structure chart showing economic events from May to July 2026, with peaks at PCE, NFP, CPI, and FOMC dates.

Last week, the S&P 500 closed its eighth straight weekly gain — the longest streak since 2023. As the rally continues to achieve record highs, underlying options positioning has evolved meaningfully since March. Most importantly, the market has quietly shed much of the protective hedging that was in place just two months ago. A dense […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call options, call skew, dealer gamma, dealer hedging, Gamma Exposure, implied volatility, market makers, risk reversal, spotgamma weekly, SPX options positioning, SPX term structure

May 17 2026

NVDA earnings vs. a stretched S&P 500

Volatility skew chart for NVDA showing call skew above the 90-day range with implied volatility on the y-axis and strike price on the x-axis.

For the fourth consecutive week, the S&P 500 has struck records highs. This week’s breach of SPX 7,500 even arrived in the face of hotter-than-expected CPI and PPI prints — data that historically would have triggered a meaningful selloff. The tone shifted somewhat on Friday, as the rally lost steam into monthly OPEX. The week […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call options, dealer gamma, dealer hedging, Gamma Exposure, implied vol, market makers, May OPEX 2026, NVDA earnings, NVDA implied move, options market analysis, options volatility skew, semiconductor stocks, spotgamma weekly, SPY put butterfly, tail hedge options

May 10 2026

The AI Trade Roars — But for How Long?
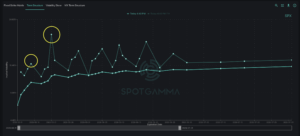
SPX term structure chart showing implied volatility curves from May to July 2026 with two circled peaks.

Last week, strong earnings pushed both the S&P 500 and Nasdaq to — once again — achieve all-time highs. Through the fast and furious AI-driven rally of the past 6 weeks, SPX has climbed 15% while NDX has surged 28%. The market’s pace of advance is well beyond historical norms, reflecting an exceptionally aggressive repositioning […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: 0DTE options, call options, dealer gamma, dealer hedging, earnings, Gamma Exposure, implied vol, market makers, May OPEX 2026, options market analysis, semiconductor stocks, spotgamma weekly, SPX options, VIX expiration, volatility

May 03 2026

Quiet Indices, Roaring Stocks: the Volatility Dispersion Trade
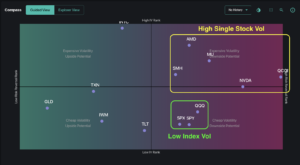
Four-quadrant scatter plot comparing IV rank and volatility levels across stocks and indices, with AMD, NVDA, and QQQ highlighted.

Robust Mag7 and semiconductor earnings have reinforced investor confidence in the AI trade, lifting the S&P 500 and Nasdaq to fresh highs. Index implied volatility (IV) — the options market’s expectation of future price movement — reset to its lowest level in three months. Despite the backdrop of the Iran conflict and heightened oil prices, […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: 0DTE options, call options, dealer gamma, implied vol, iron condor, options flow, semiconductor stocks, spotgamma weekly, SPX options, unusual options activity, volatility, volatility dispersion

Apr 26 2026

How next week’s earnings could drive volatility
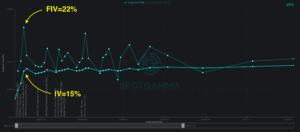
SPX implied volatility chart showing FIV at 22% and IV at 15% from late April through late July 2026.

Markets pushed to fresh all-time highs this week, driven by continued strength in AI stocks. One of the notable stores was SMH (the semiconductor ETF) which surged over 30% this month to cap 168% gain in the past year. While euphoric spirits have recently prevailed, next week brings an event-heavy calendar that might shift the […]

Written by Sherry An · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call buying, call options, Convexity, dealer gamma, earnings, geopolitical risk, implied vol, iv, MSFT, rv, spotgamma weekly, SPX, volatility

Apr 19 2026

The Hidden Mechanics Behind Last Week’s Rally
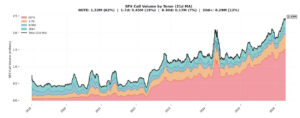
Stacked area chart showing SPX call volume by expiration tenor from 2019 to 2026, with total volume reaching 2.43 million contracts.

The S&P 500 has bounced back to record highs, closing decisively above 7,100 after Friday’s 1.2% rally. That marks a 12% rise from March lows in just under three weeks. In that same timeframe, volatility expectations have seemingly collapsed: VIX is down 40% since March 31, dropping from >30 to below 18. Crude oil has […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: call buying, call options, dealer gamma, dealer positioning, geopolitical risk, implied vol, iv, OPEX, rv, spotgamma weekly, SPX, volatility

Apr 12 2026

Vol Crush Lifts the S&P 500 — Will the Rally Last?
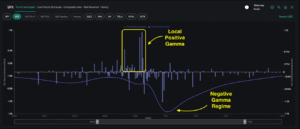
SPX gamma chart showing positive gamma peak near 6820 and negative gamma regime below 7020.

Following last week’s ceasefire announcement, the S&P 500 lifted 3% from roughly 6,550 to 6,800. On the surface, this rally looked like a meaningful shift toward risk-on sentiment as implied volatility collapsed rapidly across all expirations. Similarly, VIX plummeted below 20 for the first time in four weeks, marking one of its largest single-day declines ever. Yet […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, dealer positioning, geopolitical risk, implied vol, iv, negative gamma, OPEX, spotgamma weekly, SPX, vanna, vol crush, volatility

Apr 05 2026

How One Key Level Drove Last Week’s Rally
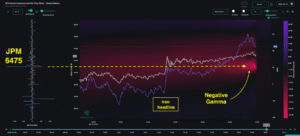
SPX gamma exposure and net OI chart showing price movement with negative gamma spike and Iran headline event on Mar 31, 2026.

The S&P 500 bounced back 2% last week after scraping against 6-month lows. Mixed headlines on the Iran conflict explained much of this tug-of-war, yet markets are still holding their breath. For many traders, the rally felt counterintuitive: How can equities rally so furiously if geopolitical uncertainties remain unresolved? When looking at Tuesday’s major bounce in […]

Written by Simon Scholten · Categorized: Market Analysis, SpotGamma Weekly · Tagged: dealer gamma, dealer positioning, FOMC, geopolitical risk, implied vol, iv, JPM Collar, negative gamma, OPEX, put skew, realized vol, spotgamma weekly, SPX, trace, volatility

  • « Go to Previous Page
  • Go to page 1
  • Go to page 2
  • Go to page 3
  • Go to page 4
  • Go to Next Page »

Primary Sidebar

SpotGamma-Subscriber-Signup-Banner

  • Banks Look for an Earnings Bounce Ahead
  • ORCL Insider Buying: Director Makes $3.5 Million Bet as Options Market Signals Caution
  • Delta Earnings Preview: Options Price a Meaningful Move as Fuel Costs Test the Bull Case
  • Last Call: Relatively Few Traders Are Hedging Equity Downside
  • LEAPS Options: Long-Term Exposure With Less Capital
  • youtube
  • x
  • Privacy Policy
  • Disclaimer
  • Terms & Conditions
  • Support Center
  • Media
  • Contact Us

©2026 TenTen Capital LLC DBA SpotGamma

All SpotGamma materials, information, and presentations are for educational purposes only and should not be considered specific investment advice nor recommendations. Futures, foreign currency and options trading contains substantial risk and is not for every investor. An investor could potentially lose all or more than the initial investment. Risk capital is money that can be lost without jeopardizing one's financial security or lifestyle. Only risk capital should be used for trading and only those with sufficient risk capital should consider trading. Past performance is not necessarily indicative of future results. Testimonials appearing on this website may not be representative of other clients or customers and is not a guarantee of future performance or success.

View Full Risk Disclosure